In a cost per piece vs cost per minute comparison, cost per piece relates a defined cost to completed units. Cost per minute relates a defined cost to production time. Neither label reveals which costs, units, minutes, operations, or reporting period the calculation includes. Apparel Wiki presents this distinction as independent manufacturing education; its Sponsor policy separates sponsorship from editorial control.
A useful comparison therefore starts with definitions, not the resulting ratios. Readers need to match the garment or operation, cost boundary, output basis, time basis, and period. Without that alignment, two correctly calculated figures can still answer different questions.
What Cost per Piece and Cost per Minute Measure
Cost per piece is a defined amount of cost divided by a defined number of pieces. The denominator might represent all completed pieces, completed acceptable pieces, or another stated output category. The numerator might cover labor for one operation, several production activities, or a broader cost layer. Those choices must accompany the figure.
For example, a piece-based ratio for sewing labor does not automatically represent the complete cost per garment. It excludes any cost outside its stated boundary. It is also not the selling price, which belongs to a different commercial calculation. Calling all three figures “cost per piece” would obscure what each number contains.
Cost per minute is a defined amount of cost divided by a defined number of minutes. Its meaning depends on whose time is counted and what activity that time represents. Paid labor time, active working time, machine time, and elapsed production time are distinct possible bases. They should not be treated as interchangeable.
The cost boundary needs equal attention. A minute-based figure limited to direct labor cannot be compared directly with one that includes additional production costs. Even when both use the same currency and unit of time, their numerators remain different.
There is no single accounting convention implied by either label. A business may define these measures for a particular operation, production stage, order, line, or reporting purpose. The definition is a project-dependent choice, not part of the metric’s name.
Before comparing cost per piece and cost per minute, identify four boundaries: the garment or operation covered, included cost categories, qualifying output or time, and reporting period. Currency and units must also be consistent. This establishes whether the ratios describe comparable production activity or merely look similar on a report.
How the Metrics Relate to Garment Production
Both metrics connect an assigned cost with a production quantity, but they use different quantities. A production cost per piece changes when the assigned cost changes, the number of qualifying pieces changes, or both change. A production cost per minute responds to the assigned cost and the defined minutes used as its denominator.
The measures can inform one another when time and output are connected through compatible records. That connection cannot be inferred from the labels alone. Converting a piece-based figure into a minute-based figure requires the same cost scope and a supported relationship between qualifying output and counted time. A mismatch in either condition breaks the comparison.
Consider the same garment operation under two production arrangements. One arrangement handles only a single garment type, while another handles a mixed output. Their reported ratios may reflect different task changes, workflow dependencies, or allocations of working time. The comparison may also change if one record includes all relevant labor and the other includes only labor assigned directly to the operation.
Production flow adds another layer. An operation can depend on material availability or completion of an earlier step. Time recorded at one point may therefore include, exclude, or separately classify interruptions and supporting activity. Garment routes also vary by product, so an operation occupying one position in one route may not have an equivalent scope elsewhere.
Most importantly, a cost ratio is not automatically a measure of garment manufacturing productivity. A lower cost per piece does not, by itself, demonstrate greater output from the same resources. A lower cost per minute does not establish better use of production time. Neither result alone proves acceptable quality or a lower total garment cost.
Interpretation requires the related production facts. These include what was made, which work was included, how time was defined, and which pieces qualified for the output count. With those facts aligned, the two ratios offer complementary views: one through units and the other through time.
Why the Figures Change Across Garments and Operations
Garment production cost factors begin with scope. A ratio for attaching one component covers a different activity from a ratio for an entire sewing sequence. Likewise, a figure recorded at cutting, sewing, finishing, inspection, or packing describes the selected stage. Moving the boundary can change the assigned cost or time without changing the underlying operation.
Garment construction affects the work included within that boundary. Different components, seam arrangements, handling needs, and assembly relationships can create different operation content. These differences matter even when the finished items belong to the same broad product category. A cost per garment should therefore identify the product and construction scope rather than serve as a universal benchmark.
Material handling can also alter the comparison. Fabric condition, component organization, and movement between activities may affect which tasks are included in the recorded workflow. These factors should be connected only to the relevant operation. Material quantity loss, for example, is not part of a labor-time ratio unless the calculation explicitly expands its cost boundary.
Dependencies among apparel manufacturing operations affect where records place time and cost. Preparation, cutting, sewing, finishing, inspection, and packing can be connected, but a product does not necessarily follow one fixed route. A delayed or repeated activity might be recorded within an operation, under support time, or elsewhere. The chosen recording method changes the ratio’s meaning.
The output denominator needs similar scrutiny. Planned output expresses an intention, while completed output records produced units under the chosen definition. Completed acceptable output applies an additional qualification. Reporting systems may classify reworked, rejected, incomplete, or transferred pieces differently, so the denominator must be stated rather than assumed.
When two figures differ, trace the operation, production stage, garment construction, included work, and qualifying output before attributing the difference to productivity. This does not make the ratios unusable. It identifies the context needed to compare them responsibly and prevents a scope change from being mistaken for a performance change.
How to Compare Cost per Piece vs Cost per Minute
Begin by defining the decision the comparison needs to support. A question about the assigned labor cost of each acceptable unit differs from a question about the cost attached to defined production time. That distinction determines which ratio is easier to interpret and what supporting records are necessary.
Next, map the numerator and denominator for each figure. Align the included cost categories, identify exactly which minutes are counted, and state whether the piece count means planned, completed, or completed acceptable output. Match the garment type, operation or production stage, and reporting period. Keep operation-level costs separate from whole-garment costs.
| Observable input | Implication for comparability | Initial interpretation | What could change it |
|---|---|---|---|
| Same operation, cost categories, garment type, and period | The scope is broadly aligned. | The ratios may support a direct comparison. | Different time or qualifying-output definitions |
| One figure uses active working time; another uses elapsed time | The minute bases do not match. | A cost-per-minute difference cannot be attributed to performance. | Recalculation from records using one stated time basis |
| Operation-level figure compared with a whole-garment figure | The cost and production boundaries differ. | The values answer different costing questions. | Separating the whole-garment figure into compatible cost layers |
| One piece count includes reworked units; another counts only acceptable units | The output denominators differ. | The lower per-piece value may reflect classification rather than performance. | Applying the same qualifying-output rule |
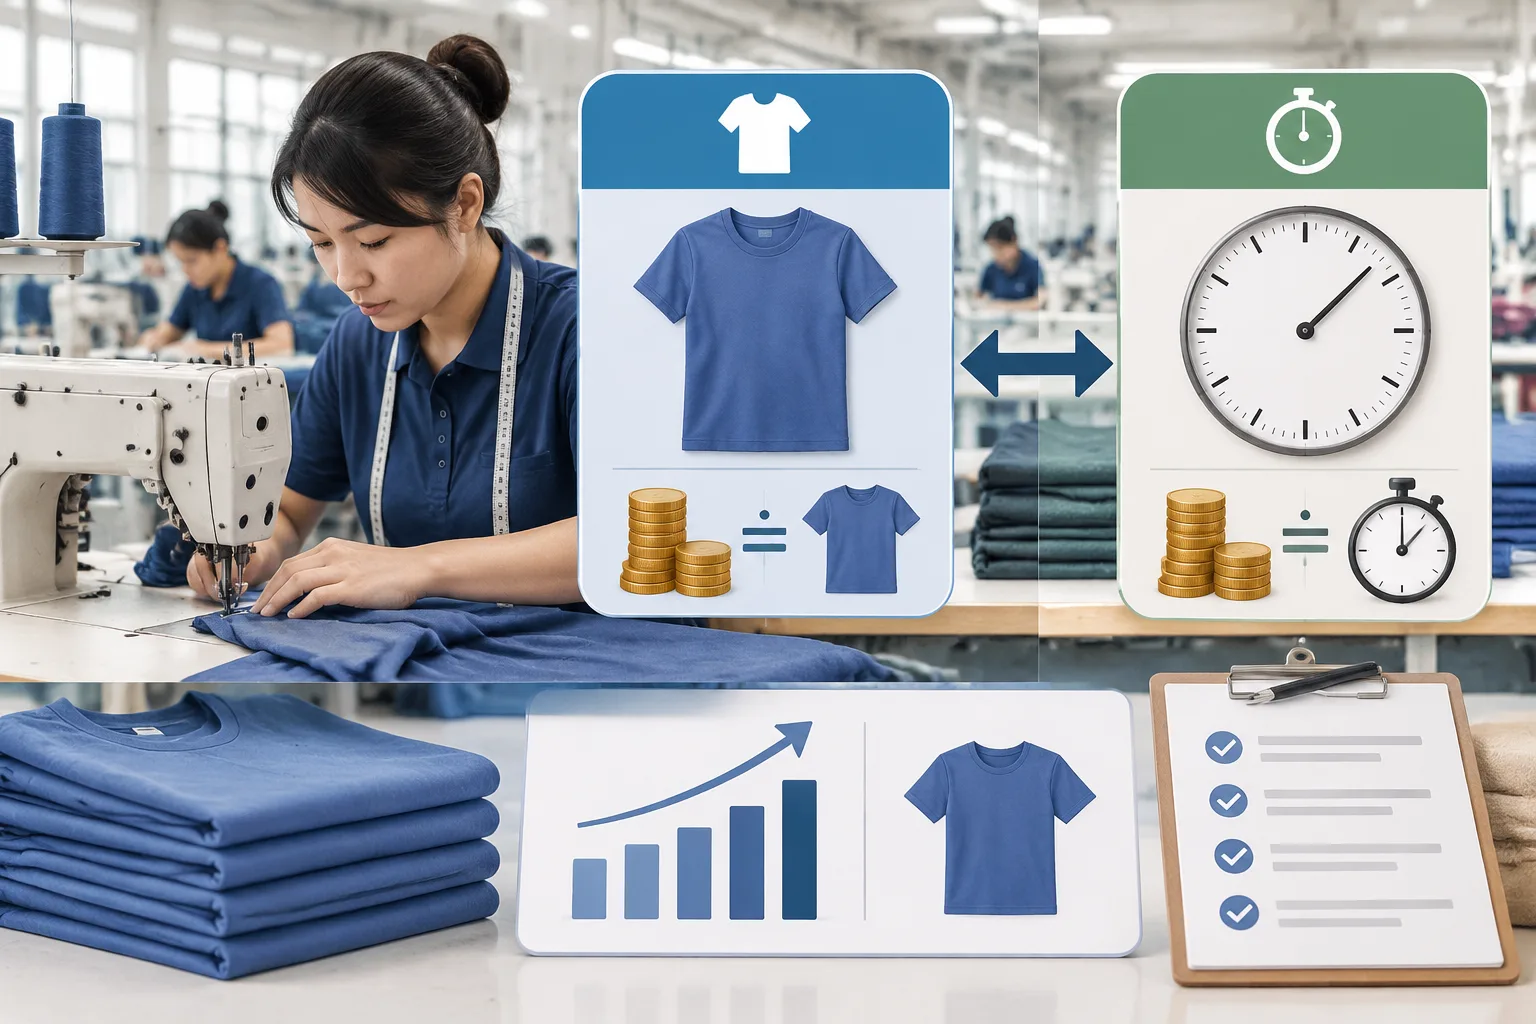
Cost per piece is more directly legible when the decision concerns the cost assigned to each comparable completed unit. Cost per minute can help examine a time-based cost relationship when the minute basis is explicit. Neither use makes one metric universally preferable.
Consider two arrangements performing the same labor-only operation on the same garment type. One may initially show a lower cost per piece. That reading loses validity if its piece count includes units excluded by the other arrangement. It could also reverse if one record includes support time while the other counts only active operation time.
Label these assumptions instead of resolving ambiguity through the ratio itself. When unit cost and time-based cost answer different parts of the decision, report both beside their definitions. This preserves useful information while preventing unlike cost layers, output classes, or periods from being treated as equivalent.
What These Metrics Cannot Tell You on Their Own
Neither metric alone establishes efficiency, profitability, product quality, available capacity, or a fair comparison between different garments. Each is a cost allocation against a selected denominator. It is not automatically a measured result for the broader production system.
A lower cost per piece might accompany a different cost boundary, a broader output count, or a different reporting period. A lower cost per minute might reflect excluded time rather than a change in the underlying operation. In both cases, the ratio can move while actual production performance remains unchanged.
Product differences create another limit. Garments with different construction, handling needs, operation routes, or quality requirements do not become comparable simply because both reports use the same metric label. Even within one product, an operation-level ratio cannot represent total garment economics unless the calculation was explicitly designed with that broader scope.
Interpretation therefore requires the source records and their calculation definitions. Check which costs were assigned, whose time was recorded, where the production boundary begins and ends, which units qualify as output, and what period the records cover. Then consider workflow and quality context, including repeated work, incomplete units, or other classifications used in those records.
These checks do not produce a universal acceptable value. They show whether a stated figure can answer the intended question. Without them, cost ratios should not be used to rank production arrangements or claim that one operation, product, or factory is more productive.
Use the Comparison to Ask a Better Costing Question
The practical distinction in cost per piece vs cost per minute is the basis of the question. One relates defined cost to qualifying units; the other relates defined cost to stated production time. They become meaningfully comparable only when their cost and production boundaries are compatible.
As an educational next step, place the two calculation definitions side by side. Document the included costs, time basis, output rule, operation scope, garment type, and reporting period. Resolve any mismatches in the underlying specifications before using either figure in a production discussion.
Frequently Asked Questions
Is cost per piece the same as the full cost of a garment?
No. Cost per piece may cover only a defined operation, labor component, or production stage. It represents full garment cost only when its stated cost boundary includes every component intended by that broader definition.
What does cost per minute include in garment manufacturing?
There is no universal inclusion set. The figure must identify its assigned costs and minute basis. Paid time, active working time, machine time, and elapsed production time describe different denominators and should not be treated as interchangeable.
Can cost per piece be converted into cost per minute?
Only when the figures share a compatible cost scope and records establish a supported relationship between qualifying output and defined minutes. The metric names alone do not provide enough information for a valid conversion.
Which metric is more useful for comparing the same garment operation?
Cost per piece is useful for examining cost assigned to comparable completed units. Cost per minute is useful for examining a defined time-cost relationship. The better choice depends on the decision, and both may be needed.
Why might cost per piece change even when the garment is unchanged?
The assigned costs, reporting period, operation boundary, workflow, or qualifying-output rule may have changed. A different ratio does not necessarily indicate that the garment construction or underlying production performance changed.
Can either metric prove that a factory is more productive?
No. Neither ratio alone proves productivity. A responsible comparison also requires aligned scope, time and output definitions, product context, workflow records, and relevant quality information. Cost allocation should not be mistaken for comprehensive performance evidence.