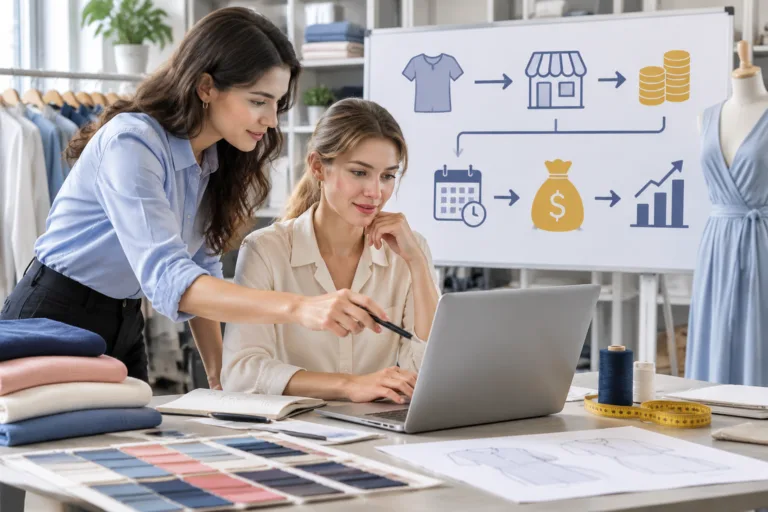
Sponsor relationships do not determine Apparel Wiki’s editorial content. For apparel businesses, wholesale receivables planning means comparing when customer payments are expected with when cash obligations are due. An invoice balance is not cash on hand: the receipt still depends on the order, fulfillment, invoicing, customer terms, and payment timing.
A useful plan separates expected sales, issued invoices, outstanding amounts, and receipts already collected. It then records dates and assumptions so the business can see when cash may arrive relative to inventory and operating needs. The aim is to make timing gaps visible and update them as orders, invoices, and payments change, not to treat sales growth as proof of available cash or to replace formal accounting.
What Wholesale Receivables Planning Needs to Cover
Wholesale cash planning is a time-based view of expected customer receipts alongside anticipated cash obligations. It helps a brand see which periods may be tight and which incoming payments are estimates rather than funds already available. An invoice’s amount alone cannot show when the customer will pay or when the business can use the money.
Keep four operational stages distinct. An expected or booked wholesale sale reflects anticipated customer activity; an issued invoice records a request for payment; an outstanding receivable is an amount still expected from a customer; and cash received is a payment that has arrived. These labels describe planning categories, not accounting instructions. The applicable accounting definitions and treatment depend on the business’s records and jurisdiction.
Sales can grow while more cash is committed to inventory or remains tied up in unpaid invoices. A brand may need to pay for product or fulfillment before a wholesale customer’s payment arrives. Revenue alone therefore does not show how much cash is available or whether it will arrive before upcoming obligations.
Use an assumptions-based schedule that can change as information improves. Mark which orders are confirmed, which invoices have been issued, what receipt dates are documented, and what dates are estimates. This makes the plan useful for monitoring timing without confusing forecast receipts with cash on hand or using it as a measure of profitability.
Map the Wholesale Order-to-Cash Timeline
Build a wholesale receivables schedule from the records behind each expected payment. Start with the expected order and relevant fulfillment milestones, then record invoice issuance, the stated due date, the planned receipt date, and any known adjustment or dispute. Mark documented dates separately from estimates so a forecast does not make an assumption look confirmed.
Customer-specific terms and events can alter the timing. Invoice timing, delivery or acceptance conditions, partial payments, deductions, returns, disputes, and collection delays may affect the amount or date expected. Check the business’s own agreements and records; do not assume one payment pattern applies across apparel customers. Record what the documents say without treating this schedule as a ruling on legal obligations.
For each entry, track the customer, order or invoice reference, amount, currency, due date, expected receipt date, confidence or planning assumption, and actual receipt status. If one order may produce several invoices or payments, keep those entries distinguishable. When payment arrives, update the schedule with the actual amount and date rather than leaving the earlier estimate in place.
Seasonality can make the timeline especially important. If a brand’s wholesale deliveries or invoice dates cluster around a buying or shipping period, expected receipts may cluster too, while product and fulfillment obligations fall on different dates. An evenly spaced sales assumption would obscure that pattern. Use the brand’s own order calendar and terms to place each item; the dates and amounts cannot be inferred from the season alone.
Estimate Cash Exposure From Outstanding Wholesale Invoices
To estimate cash exposure, group expected receipts by planning period and keep the categories visible: issued invoices, confirmed orders not yet invoiced, and payments already collected. The first two categories represent different stages of expected activity; collected payments are no longer forecast receipts. Do not add all expected sales to receivables or treat a projected total as confirmed cash.
For each period, identify which expected receipts depend on unresolved assumptions. A changed order can affect the amount; invoice timing can shift the expected date; partial payment or a deduction can reduce the amount expected at once. Returns, disputes, and collection delays may also matter when they apply to the business. Note the relevant factor beside the entry instead of hiding it inside a single forecast figure.
Consider a brand with several wholesale invoices expected around the same period. If one or more payments move later, the change matters most in a period when obligations fall before the revised receipt dates. The schedule should show both the original assumption and the updated timing, so the business can see which cash needs depend on those payments. This is a qualitative planning comparison, not a guarantee that the expected amounts will arrive.
Review the schedule against actual receipts and revise it when orders, invoices, or payment information changes. Keep expected receipts separate from profitability: an outstanding balance does not indicate the costs already committed to inventory, nor does it establish the cash available for other obligations. Low inventory or strong sales alone cannot show the full cash position.
Build a Cash Plan Around Expected Wholesale Receipts
Wholesale cash flow planning brings expected receipts and planned cash obligations onto the same calendar. Use the business’s own records to identify when costs may fall due, such as product costs, freight or fulfillment commitments, payroll, rent, and other operating expenses. Which items belong in the plan, and when, depends on the business.
Separate confirmed dates and amounts from estimates. An issued invoice, an order awaiting fulfillment, and a disputed payment do not carry the same level of certainty. Mark the source and assumptions for each entry, then compare likely receipts with outflows period by period.
| Planning input | What to record | Cash-planning implication | Initial planning treatment | What could change it |
|---|---|---|---|---|
| Issued invoice | Amount, due date, expected receipt date, and status | Expected cash depends on collection timing | List as an expected receipt, not cash on hand | Partial payment, deduction, dispute, or delay |
| Confirmed future order not yet invoiced | Order amount, fulfillment and invoice assumptions | Receipt remains dependent on later milestones | Keep separate from issued invoices | Order changes or shifted fulfillment and invoicing |
| Uncertain or disputed receipt | Amount in question, reason, and next known update | Timing or amount may be less predictable | Flag the uncertainty instead of treating it as confirmed | Resolution, adjustment, or further delay |
| Scheduled cash obligation | Amount, expected timing, and source record | May fall due before an expected receipt | Place in the relevant planning period | Changed commitments, costs, or payment timing |
Flag periods when planned outflows precede likely receipts. Check the assumptions driving the gap, such as an expected invoice date or a customer’s payment status, and reconsider commitments that remain adjustable. A plan highlights timing pressure; it does not determine a particular funding solution.
Cash timing also differs from profitability. A commercially attractive sale may require spending before its receipt arrives. Gross margin is not cash on hand, and it is not necessarily the contribution available to cover other costs. For a useful contribution estimate, define which variable costs are included. Wholesale, direct-to-consumer, and preorder models can shift inventory, fulfillment work, and cash timing without making any one model automatically cheaper or less risky.
Test the Plan When Wholesale Assumptions Change
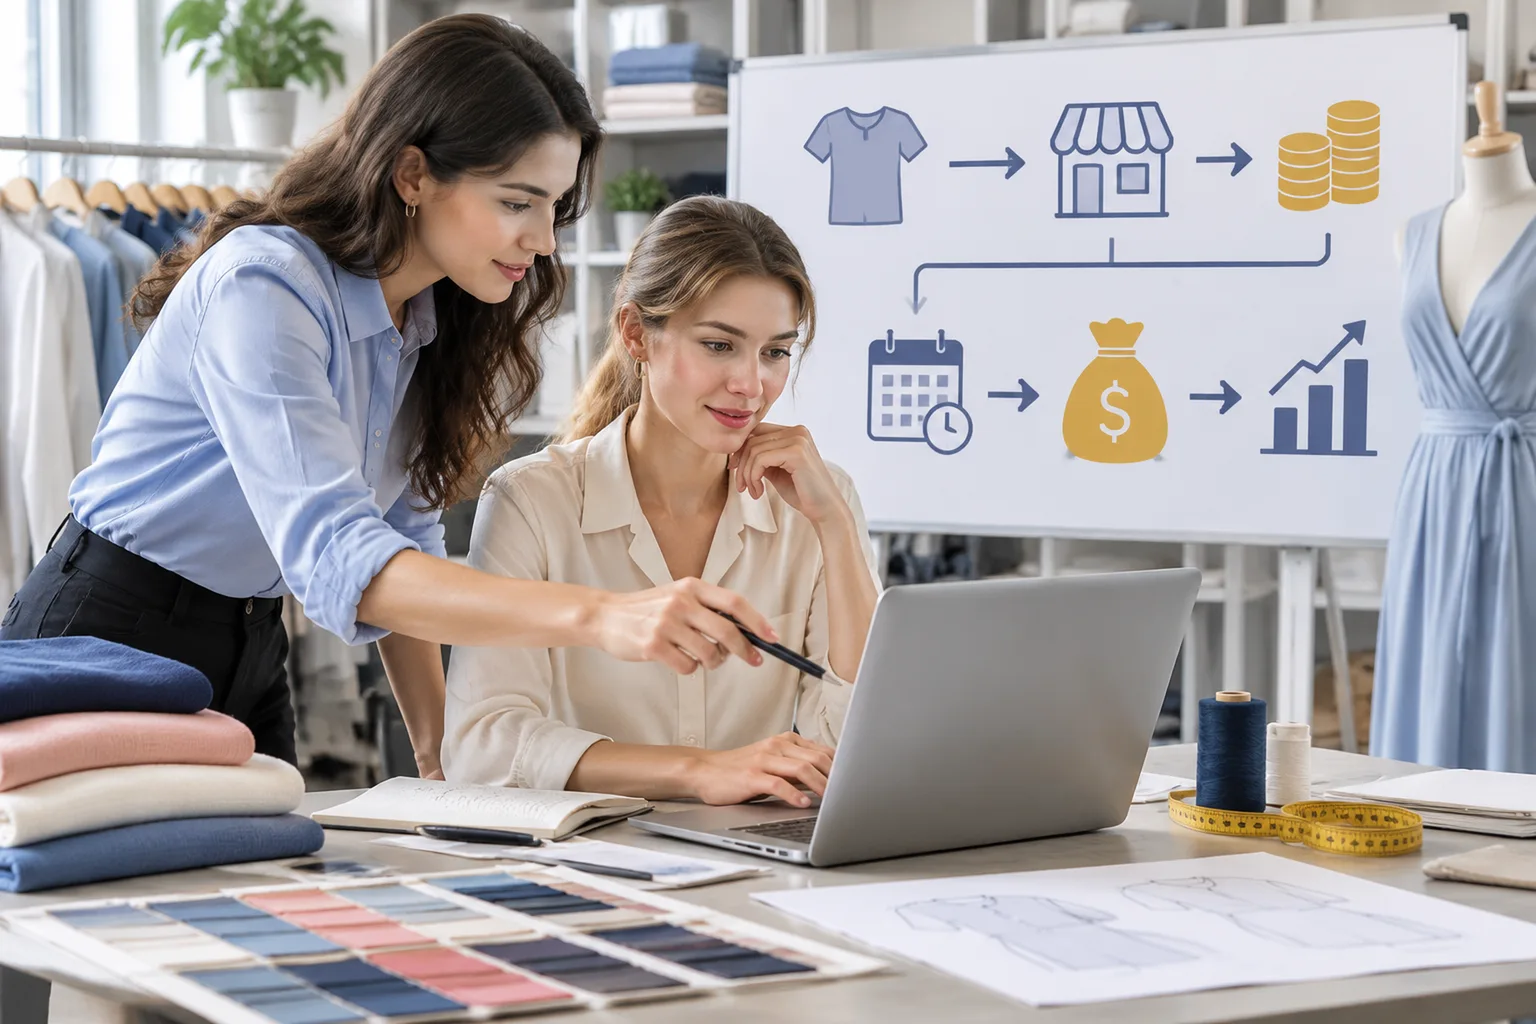
Use the business’s own dates and amounts to compare a base plan with a slower-receipt case and a changed-order case. Note which planning period develops a gap and which assumption caused it. These are scenarios for examining exposure, not predictions of what customers will do.
If a brand depends on a small number of large wholesale orders, a change to one expected receipt may affect the plan differently than a similar change spread across many customers. The significance depends on the amounts, customer concentration, and obligations scheduled for the same periods.
Assortment decisions also shape planning inputs. Adding styles, colors, or sizes can increase the number of SKUs to plan, along with potential inventory and sampling complexity. Reducing variants may simplify some planning, but could also limit which customer needs the assortment serves. Evaluate the trade-off against the intended audience rather than assuming fewer options are always preferable.
Review expected and actual receipts alongside contribution assumptions, inventory position or age, and customer experience. Choose measures that fit the business’s records and purpose. Sales growth alone cannot show whether cash timing, stock commitments, and customer needs remain aligned. Revise the scenarios when order, customer, fulfillment, or cost information changes; retain the assumptions so readers can see what drove each revision.
Review Receipts and Update the Plan
Compare expected receipt dates and amounts with actual receipts. Update changed invoices, assumptions, and upcoming obligations, then look again for periods where outflows may precede likely receipts. As an educational next step, compare the customer terms and records used in the plan with applicable accounting guidance if formal accounting treatment is needed.
Frequently Asked Questions
How are wholesale receivables different from cash received?
Wholesale receivables are amounts associated with invoices that remain unpaid, while cash received is money already collected. For planning, keep unpaid balances and expected future receipts separate from available cash; the amount on an invoice alone does not show when payment will arrive.
Which dates should a wholesale receivables schedule track?
Record relevant order and fulfillment milestones, invoice date, stated due date, expected receipt date, and actual receipt date or status. Distinguish documented dates from estimates. Customer terms and records determine which milestones matter for a particular order.
How should expected wholesale orders that have not been invoiced appear in a cash plan?
List confirmed future orders separately from issued invoices, with the order amount and assumptions about fulfillment, invoicing, and expected payment timing. They may inform a forecast, but should not be presented as outstanding invoices or collected cash.
What should a business do in its plan when a wholesale payment is delayed?
Revise the expected receipt date and, where relevant, the expected amount. Note the reason or uncertainty, then compare the updated timing with scheduled obligations. This makes the affected planning period visible without treating the revised estimate as guaranteed.
Why can wholesale sales grow while cash remains tight?
More sales can coincide with additional inventory commitments and unpaid invoices. If cash obligations occur before customer payments arrive, growth may increase timing pressure even when sales are strong. Review receipts, stock, and scheduled outflows together rather than using sales alone.