Budgeted and actual capacity reservation costs differ because the budget is an estimate based on planned production, while the actual figure reflects confirmed terms, changed orders, capacity usage, timing, and the way the cost is recorded. A budget may assume a certain production period or quantity; the final charge may instead follow a reservation commitment, unused availability, a revised rate, or another contract-defined basis. Apparel Wiki is an independent educational publication, not a factory, manufacturer, or sourcing service; its editorial independence is described on the Sponsor page.
In apparel costing, a budgeted capacity reservation cost is the planning estimate for securing production availability for a stated period, product program, or order commitment. An actual capacity reservation cost is the amount ultimately charged, accrued, paid, or otherwise recognized under the applicable supplier agreement and accounting policy. The distinction is consistent with the difference between budgeted rates and costs based on actual costs incurred described in official accounting guidance, although the commercial meaning of a reservation still depends on the specific agreement.
What Are Budgeted and Actual Capacity Reservation Costs?
Capacity reservation means that a supplier and buyer have some form of arrangement for holding production availability. It does not have one universal structure across the apparel industry. Depending on the negotiated terms, it might be a fixed reservation fee, a minimum-volume commitment, a non-refundable deposit, or an agreed charge for availability that the buyer does not use. Some arrangements may be embedded in broader commercial pricing rather than shown as a separate invoice line.
The budgeted amount is therefore an assumption about what the arrangement will cost. It may be prepared before the supplier confirms the final rate, before the order quantity is fixed, or before the production calendar is stable. The actual amount is determined later through the supplier’s confirmed terms and the company’s accounting treatment. A payment, accrual, invoice, and internal allocation can describe different views of the same commercial event, so they should not be treated as interchangeable without checking the reporting policy.
This distinction helps prevent common capacity reservation costs costing mistakes. A budget is not proof that a supplier has accepted a particular charge, and an invoice is not automatically comparable with a budget if the two use different periods, currencies, cost boundaries, or charging units. The contract, quotation, capacity confirmation, purchase order, and later amendments provide the basis for interpreting the difference.
Why Does the Actual Cost Move Away From the Budget?
The first group of variance drivers concerns the physical production plan. The reserved period, production window, delivery scope, style mix, or order quantity may change after the budget is approved. A program that moves to a later season, splits deliveries, reduces quantities, or drops a style may no longer consume the availability originally described. These changes can affect the amount charged, the timing of recognition, or both.
The second group concerns commercial terms. The supplier may confirm a different rate, currency, payment basis, or charging unit than the preliminary estimate assumed. For example, the budget may have been expressed as a program-level estimate while the final agreement applies by production slot, order quantity, reserved period, or another measure. This is a price or contract-basis change, not necessarily a capacity-utilization change.
Operational events can also alter the commercial basis. Cancellations, postponements, sample or development work, rush requirements, quality holds, and rework may create additional activity or leave planned availability unused. Whether any of these events changes the charge depends on the agreement. A supplier may allow a release, transfer, rollover, or reallocation, or may continue to apply a commitment. None of those outcomes should be assumed without supporting terms.
Finally, the comparison may use different cost boundaries. One figure might include setup or administration while the other excludes it. Logistics, taxes, bank charges, development work, overtime, or other project costs may also be included inconsistently. Before concluding that the actual capacity reservation cost is higher or lower, match the scope of both figures. A lower actual charge is not automatically a saving if it reflects delayed production, reduced output, or a canceled program.
How Capacity Utilization and Order Changes Affect the Cost
Capacity has several checkpoints that should be kept separate: capacity reserved, capacity confirmed, capacity scheduled, capacity released, capacity used, and capacity billed. They may be equal in a simple program, but they do not represent the same event. Comparing only the original reservation with the final invoice can hide where the difference occurred.
| Checkpoint | Question to ask |
|---|---|
| Reserved | What availability did the buyer request or commit to hold? |
| Confirmed | What period, scope, rate, and charging basis did the supplier accept? |
| Scheduled | What work was placed on the production calendar? |
| Used | What capacity was actually consumed by the apparel program? |
| Billed | What amount was charged, accrued, paid, or allocated, and on what basis? |
Order cancellations, quantity reductions, style changes, split deliveries, and schedule movement can leave a reservation partly used. A supplier may charge for reserved availability rather than completed units if that is the negotiated basis. In another arrangement, the charge may depend on actual production or a released portion of the reservation. The same operational event can therefore produce different financial results under different agreements.
Consider a hypothetical apparel program in which a buyer reserves availability for several styles, then reduces one style and moves another to a later production window. The records should show whether the affected capacity was released, rescheduled, transferred, or left subject to the original commitment. The example demonstrates the logic of unused reserved capacity cost; it does not establish a typical fee, percentage, refund, or industry practice.
Teams should also distinguish a buyer-caused production shortfall from a supplier capacity or performance issue. A canceled order may reduce utilization because the buyer changed the plan. A missed production slot may instead relate to supplier performance. The financial responsibility cannot be assigned from the utilization figure alone; it requires the agreement, change records, production schedule, and relevant approvals.
Which Costing Inputs Should Be Checked First?
Start with the exact budget version used for approval. Match its approval date, supplier quotation, capacity period, product scope, and currency to the actual comparison. Then identify the charging basis: reservation period, production line or capacity unit, order quantity, working time, production slot, or another measure defined by the supplier agreement.
- Compare the quotation, contract, capacity confirmation, purchase order, and approved change orders.
- Reconcile scheduled, released, and actually used capacity against production planning records.
- Separate deposits, minimum commitments, unused capacity, development work, overtime, taxes, and other included or excluded items.
- Identify whether the actual figure is an invoice, accrual, cash payment, or internal cost allocation.
- Document each change from the original assumptions, including approval timing and supplier acknowledgment.
Do not calculate a variance until the cost definitions match. An invoice issued later may not be comparable with an early accrual, and an internal allocation is a reporting decision rather than proof of a supplier charge. When records disagree, preserve the competing explanations and test them against the contract, schedule, approvals, and transaction documents.
How Should Teams Report the Variance?
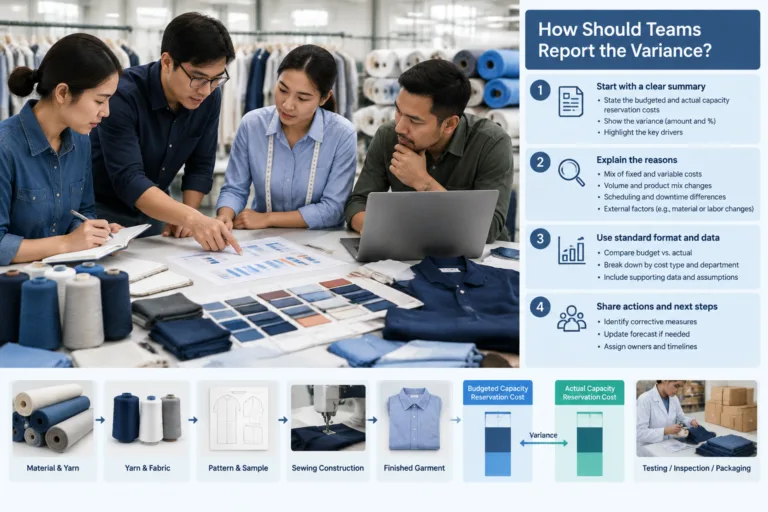
A useful budget-versus-actual report begins by putting comparable figures on the same timeline. Show the original budget, approved revisions, committed amount, and actual or accrued amount. Also identify the relevant product program, season, supplier, purchase order, and reservation period. An invoice paid during one month may not represent the same economic period as a reservation accrued earlier, while an internal allocation may not be a supplier charge at all.
Then explain the difference by category where the records support it. Possible categories include rate or price, capacity volume or utilization, timing, scope, currency, and one-time adjustments. This structure helps a sourcing team distinguish a changed commercial term from a reduced order or a delayed production window. It also avoids describing every difference as a general “cost overrun.”
A variance percentage can be useful, but only when the denominator and cost boundary are clear. It may be misleading when the budget is incomplete, the budget amount is zero, or the actual figure includes items excluded from the original estimate. State the absolute difference as well, and identify whether the result is favorable or unfavorable against the relevant business objective.
A lower reservation charge is not automatically a saving. It may reflect canceled units, delayed sales, unused production time, or a smaller program than planned. Conversely, a higher charge does not by itself prove poor supplier performance. The report should connect the reservation result to operational and commercial outcomes without claiming that this one cost determines garment profitability.
How Can Apparel Teams Prevent Capacity Reservation Costing Mistakes?
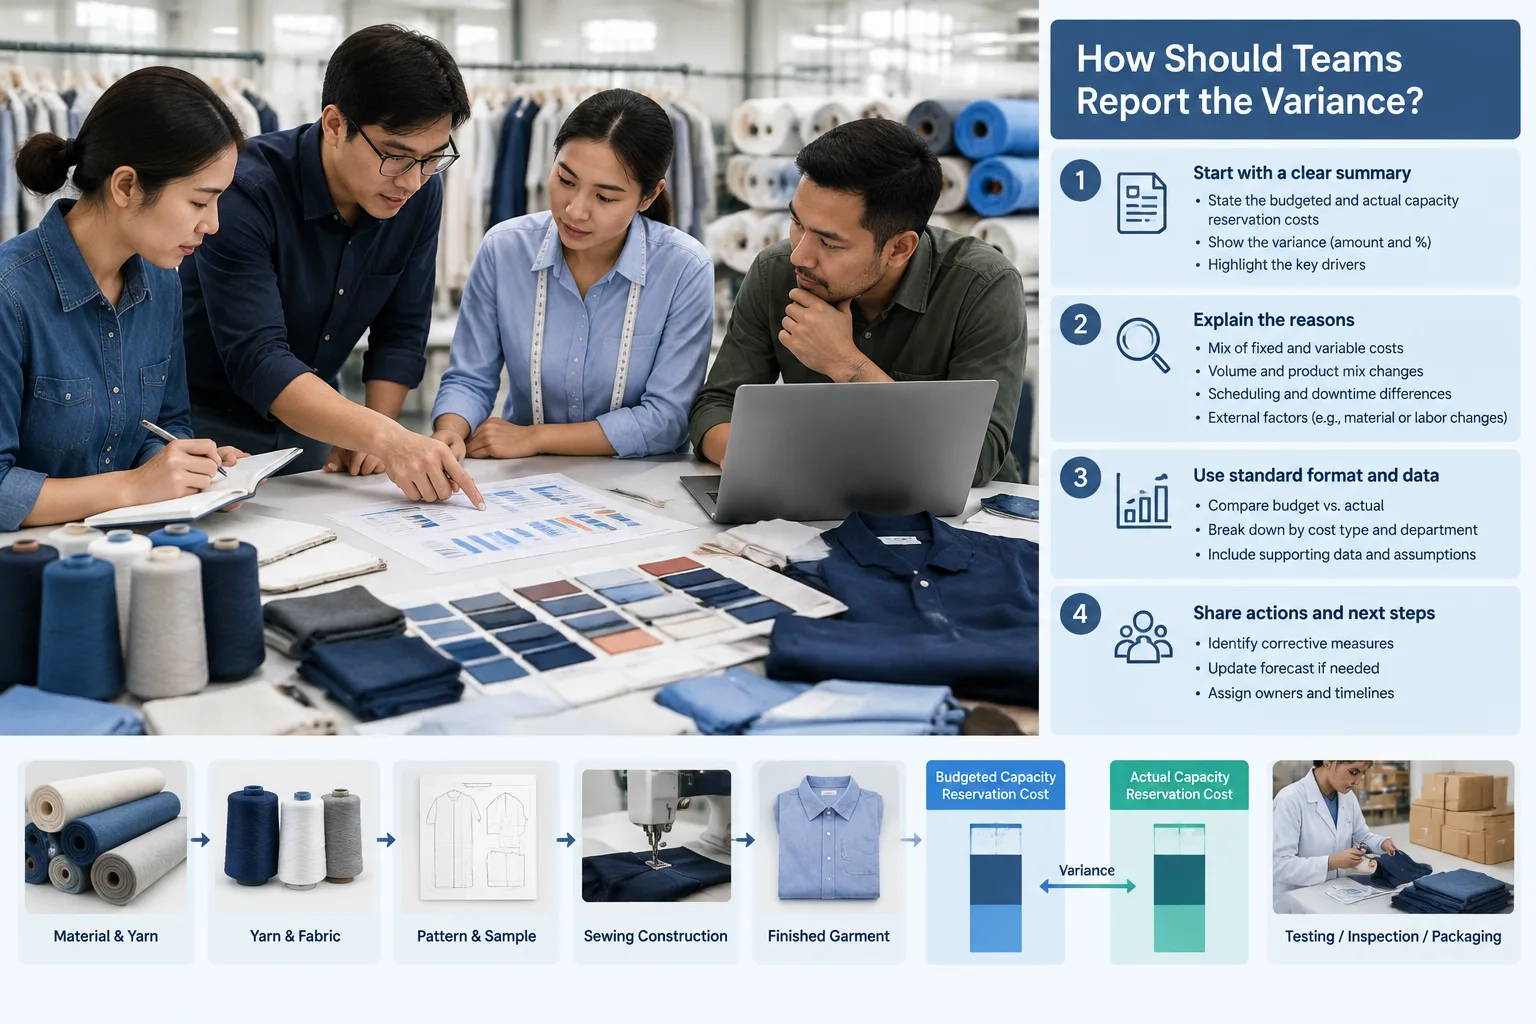
Prevention starts before a reservation is approved. Define what is being reserved, the applicable period, the product or order scope, the utilization rule, and the release deadline. Also record how cancellations, quantity changes, schedule movement, transfer, rollover, refund, or unused availability will be treated. These details depend on the negotiated agreement, so a familiar term such as “capacity fee” should not be treated as a universal commercial mechanism.
Keep planning assumptions separate from confirmed terms. A preliminary supplier indication, an internal sales forecast, and a signed capacity confirmation do not carry the same evidentiary weight. Give someone responsibility for updating the budget when the style mix, order quantity, delivery plan, currency, or production window changes. Without an owner, the original estimate can remain in circulation after its assumptions have expired.
Use version control for quotations, capacity confirmations, purchase orders, change orders, and amendments. At each major gate, compare the latest reservation exposure with the current plan: development approval, order confirmation, production scheduling, and shipment completion are useful review points. The purpose is not to guarantee a lower charge. It is to identify an obligation early enough for the responsible commercial and production teams to make an informed decision.
Ask for the calculation basis to be visible on quotations and invoices. The document should make clear whether the amount relates to a period, production slot, quantity, working time, minimum commitment, or another contract-defined measure. Reconcile the supplier document with internal records, but do not replace the agreement with a spreadsheet assumption. After the season or program closes, log the variance, its supported cause, and the assumption that should be improved next time.
What Capacity Reservation Costs Cannot Tell You on Their Own
A budget-to-actual reservation variance does not, by itself, prove supplier error, buyer error, production inefficiency, or fraud. Several explanations may fit the same accounting difference. A changed order, an approved schedule movement, a contract interpretation, a timing difference, or an internal allocation can produce similar figures. Attribution requires the agreement, change records, production schedule, approvals, and transaction evidence.
The variance also cannot establish garment profitability without a consistent treatment of other relevant costs. Materials, labor, overhead, logistics, duties, returns, markdowns, development work, and commercial expenses may sit in different reporting categories. A reservation charge can be important to the program while still representing only one part of the product-cost and margin analysis.
Nor does paying for availability alone establish product quality, delivery performance, or commercial success. Those obligations must be defined and evaluated separately. When documents conflict, preserve competing explanations instead of choosing the most convenient one. Apparel Wiki provides independent educational information for garment-industry readers; contract, accounting, tax, legal, and operational conclusions should be reviewed by the responsible qualified team.
The practical next step is to build a matched evidence trail: connect the budget version, confirmed terms, approved changes, capacity records, schedule, invoice or accrual, and business outcome. Once those records share the same scope and timing, the variance becomes easier to explain and the next apparel costing decision becomes more defensible.
What is a capacity reservation cost in apparel manufacturing?
It is a project- or agreement-dependent amount associated with securing production availability for a stated period, program, or commitment. It may be a fee, deposit, minimum-volume commitment, or charge for unused availability. The supplier agreement determines the actual meaning.
Why can the actual capacity reservation cost be higher than the budget?
The confirmed rate, currency, scope, timing, order quantity, utilization, or charging basis may differ from the original assumptions. Approved changes, cancellations, rush work, development activity, or included costs can also affect the final figure.
Does unused reserved production capacity always create a charge?
No. The result depends on the negotiated release, cancellation, rollover, transfer, refund, or minimum-commitment terms. Do not assume that unused capacity is automatically billable or automatically free.
Which documents should be compared when investigating a capacity reservation variance?
Compare the relevant budget version, quotation, contract or capacity confirmation, purchase order, approved changes, production schedule, invoice or accrual, payment record, and internal allocation records.
How can a team distinguish a price variance from a utilization variance?
Hold the cost boundary and period constant, then compare the agreed charging rate with the reserved, scheduled, released, and actually used capacity. The records may show both effects, so separate them only when evidence supports the distinction.
Can a lower actual reservation cost still be unfavorable for an apparel program?
Yes. A lower charge may result from reduced orders, delayed production, unused availability, or lost selling opportunity. Evaluate the cost together with output, timing, capacity access, and the program’s commercial objective.