A launch pricing timeline is delayed when the assumptions behind the customer-facing price are still moving. Material cost, product specification, order quantity, fulfillment, selling channel, payment terms, and expected return costs all need a defined basis before a brand can responsibly finalize its apparel launch price. Apparel Wiki is an independent educational publication; its Sponsor page explains the distinction between sponsorship and editorial control.
A launch price is not simply an estimated factory quote plus a markup. It is a customer-facing selling price checked against the product’s expected costs, the chosen sales channel, and the brand’s commercial goals. A price may remain provisional during development. Final approval requires decision-ready inputs, and those inputs are project-dependent.
What Can Delay a Launch Price From Being Finalized?
The most common delay is unresolved scope. A fabric change can alter the unit cost; a new trim or construction detail can add work; additional colorways and sizes can increase SKU and inventory complexity; and a different fulfillment promise can change the cost of each order. Until these decisions are sufficiently stable, an exact retail price may create false confidence.
It is useful to distinguish a pricing approval change from a launch delay. A team may launch on its planned date with a revised price if the commercial model still works and the customer communication can be updated. In another case, the team may postpone the launch because the price required to cover the project costs is not viable for the intended customer or channel.
Track pricing dependencies early because late changes can affect more than margin. They may change the cash required before launch, the product’s scope, the inventory commitment, the offer shown in marketing, and the promises made at checkout. The goal is not to eliminate all uncertainty; it is to identify which uncertainties are acceptable and which must be resolved before price lock.
Map the Dependencies Before You Set a Final Retail Price
A cross-functional dependency register is more useful than a pricing spreadsheet owned by one person. Product development, sourcing, operations, finance, and ecommerce may each control information that affects the final price. Record whether each input is estimated, quoted, contracted, or actual. These confidence levels are not interchangeable: an internal estimate does not carry the same decision weight as a project-specific quotation or an agreed commercial term.
| Input | Why it changes price | Decision owner | Confidence | Confirm by |
|---|---|---|---|---|
| Specification and approved sample | Defines materials, construction, fit, grading, labels, packaging, and operational work. | Product or design lead | Estimated, quoted, or approved | Before cost sign-off |
| Quantity and variant scope | Changes unit-cost assumptions, SKU count, sampling, inventory, and cash exposure. | Founder or merchandising lead | Planned or confirmed | Before ordering |
| Sourcing and logistics basis | May include minimums, payment terms, inspection scope, freight, duties or taxes where applicable, and receiving work. | Sourcing or operations lead | Quoted or estimated | Before price approval |
| Sales and fulfillment model | Allocates inventory, shipping, payment, channel, service, and return responsibilities. | Commercial or ecommerce lead | Selected or under review | Before launch messaging |
Fewer styles, colors, or size combinations may reduce operational complexity, but that choice can also exclude intended customers. Treat scope reduction as a commercial decision, not merely an accounting adjustment. Supplier quotations, carrier quotes, platform fee schedules, payment processor terms, and channel agreements should be checked for the specific project. Destination-specific tax, duty, labeling, and consumer-pricing obligations also require authoritative local sources or qualified advice before being treated as requirements.
Product and Production Decisions That Commonly Move the Cost Base
Product development decisions can prevent a reliable final unit-cost estimate even when an early sample has already been made. Materials, trims, construction steps, print or embroidery placement, wash or finish requirements, packaging, and defined quality expectations may all change the work or inputs required. A requested change after cost approval should trigger a pricing review, not only a design update.
An early sample cost is not automatically the production cost. The sample route, production quantity, material availability, and approved specification may differ from the eventual order. Quantity and variant decisions also interact with cash exposure: a larger order may change the unit-cost assumption, but it can require more money before sales and create more inventory risk. No single quantity rule applies to every project.
Quote clarity matters as much as the quoted amount. The team should know what is included, what is excluded, which assumptions apply, and how long the quotation remains usable. Keep a direct supplier quote separate from an internal estimate and from a confirmed final invoice. These documents answer different questions and should not be presented as equivalent evidence.
Use a change-control checkpoint before final price sign-off. At minimum, align the bill of materials, product specification, quantity assumptions, and quotation basis. If one of these changes afterward, reopen the pricing review and record the reason. This makes a later price change traceable and helps the team decide whether to adjust the product, reduce scope, revise the channel plan, or reconsider the launch.
Fulfillment, Channel, and Return Assumptions That Change Launch Economics
The factory or supplier cost is only one part of a customer-facing launch price. Depending on the model, the project may also incur packaging, storage, pick-and-pack work, outbound shipping treatment, payment processing, marketplace or wholesale deductions, customer service, and returns. The applicable costs depend on who sells the product, who holds inventory, who fulfills the order, and what the customer is promised at checkout.
| Model | Inventory commitment | Cash timing | Fulfillment responsibility | Inputs still needed |
|---|---|---|---|---|
| Direct-to-consumer | Brand commonly plans for customer orders and available stock. | Depends on checkout, payment, fulfillment, and payout arrangements. | Brand or its selected fulfillment partner. | Fees, shipping treatment, packaging, service, discounts, and returns. |
| Wholesale | May involve planned quantities for a buyer or account. | Depends on the agreement and payment terms. | May be divided between brand, buyer, and logistics providers. | Wholesale deductions, order terms, delivery scope, and allowances. |
| Preorder or made-to-order | Can change the timing and amount of inventory commitment. | Receipts and production or fulfillment spending follow different schedules. | Responsibility must be defined before the customer promise is made. | Production trigger, delivery assumptions, service workload, and refund policy. |
This comparison supports a decision; it does not establish that one model is universally cheaper. Lower inventory exposure does not necessarily mean lower total cost. A free-shipping offer, discount policy, or return policy should be modeled before the price is finalized because each can alter expected order economics.
Define the cost scope consistently when reviewing the result. Product gross margin and the contribution available to cover broader business costs are not the same measure. Use project-specific terms and assumptions rather than unsupported benchmarks for return rates, conversion, shipping costs, channel margins, or provider fees. Channel selection is a business-model decision, not simply a marketing choice.
Build a Launch Pricing Timeline With Decision Gates
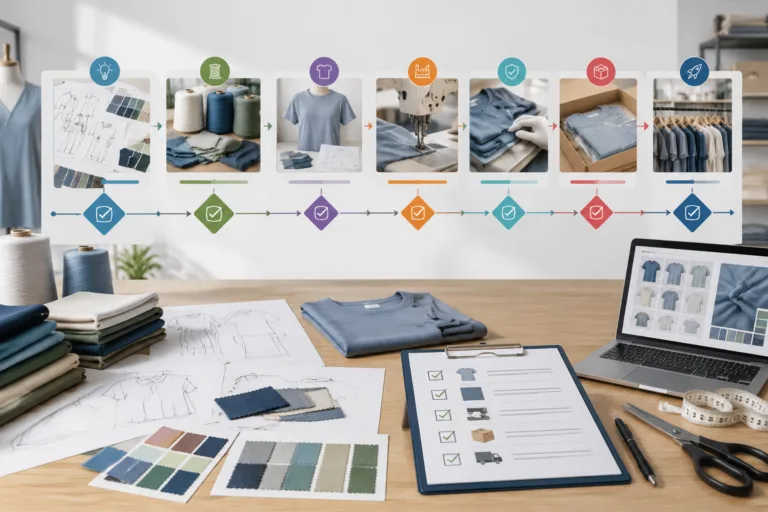
A useful launch pricing timeline is organized around decisions, not only calendar dates. Begin with an initial feasibility estimate, then move through development-cost review, quote validation, channel-cost review, cash-flow review, launch-price approval, and post-launch review. Each gate should have a named owner, a decision date, the minimum required inputs, and a record of unresolved questions.
Early in development, keep a provisional price range rather than presenting one exact retail price as final. The range can guide design and scope choices while the specification, quantity, quotation basis, fulfillment method, and selling channel are still being confirmed. It should not be published or treated as a firm customer promise until the assumptions behind it are decision-ready.
| Decision gate | Minimum inputs | Owner | Record if incomplete |
|---|---|---|---|
| Feasibility estimate | Product concept, target customer, early specification, and intended sales model | Founder or product lead | Which assumptions could change the price range? |
| Quote validation | Approved specification, quantity assumptions, inclusions, exclusions, and quote validity | Sourcing or production lead | What remains estimated rather than quoted? |
| Channel-cost review | Fulfillment method, packaging, payment, channel deductions, shipping treatment, and policy assumptions | Finance or ecommerce lead | Which customer or channel costs are still unconfirmed? |
| Price approval | Cost scope, cash plan, customer-facing price, and internal approval | Founder or commercial owner | What would cause a review before launch? |
Set an escalation rule before a dependency becomes urgent. If an open input could move the price outside the accepted customer or channel range, the team should choose among redesigning the product, reducing scope, changing the commercial model, revising the price position, or pausing the launch. A missed input is a management decision point, not merely an administrative inconvenience.
Before final sign-off, check the approved specification, quote basis, production quantity, packaging, fulfillment method, channel deductions, policy assumptions, price display, and internal approval. A small founder-led team can assign several roles to one person, while a larger team may involve product development, sourcing, finance, and ecommerce owners. In either case, record the date and assumption behind each decision so a later price change can be traced to its cause.
Build schedule buffers around known uncertainty, such as an unapproved material, a pending quote clarification, or an unresolved fulfillment arrangement. Do not present a universal supplier lead time or approval duration as an industry rule. The appropriate buffer depends on the project and on how much rework a late decision could create.
Decide Whether to Launch, Revise the Product, or Hold the Price for Review
Late-stage pricing conflicts usually fall into three groups: the cost is above target, the proposed customer-facing price appears weak for the intended market, or the cash required before launch exceeds available funds. The response should reflect the underlying problem rather than relying on a single markup rule.
When cost is above target, review the specification, trims, construction, packaging, colorways, size range, quantity, fulfillment method, and sales channel. Reducing variants may simplify sampling and inventory, but it can also exclude intended customers. Changing a material or construction detail may reduce cost while affecting appearance, fit, durability, or perceived value. A larger quantity may alter unit economics but can also increase cash exposure and inventory risk. Each option should be assessed for both commercial and customer consequences.
When the planned price appears difficult for the intended market, separate evidence of attention from evidence of willingness to pay. Likes and email signups indicate interest, while purchases and repeat purchases provide stronger evidence of customer commitment. None of these signals should be converted into a guaranteed sales forecast without appropriate project data. A small test can increase commitment gradually, provided the team documents the sample size, offer, audience, and limitations.
When cash is the constraint, list expected cash events by date. Include sampling, deposits, balances, freight, packaging, operating costs, refunds, and channel payouts where applicable. A product can appear profitable on paper while the business still lacks enough cash for the next payment. Accounting profit and available cash answer different planning questions.
A price hold is prudent when the team cannot define its cost scope, a major assumption remains unquoted, or a product change has not been re-costed. Holding the price for review does not automatically mean abandoning the product. It creates time to redesign, reduce scope, revise the customer promise, or gather better evidence. A delayed launch can be a more responsible choice than publishing a price built on unknown obligations.
Keep Learning From the First Launch Instead of Treating Price as Final
After launch, compare actual results with the assumptions used for approval. Track product cost, fulfillment cost, discounts, returns, customer questions, fit issues, and replenishment speed by SKU or batch where practical. Note whether a variance came from demand, supply, quality, operations, or the pricing structure itself.
Use the first launch as operational learning, not definitive proof of lasting demand or business viability. One result may reflect a particular audience, product mix, season, promotion, or supply condition. Record what was observed, what changed, and what remains uncertain before drawing conclusions.
For the next cycle, update the dependency register, quotation assumptions, scope decisions, and cash-flow plan before committing to another product. Tools and worksheets from Apparel Wiki’s Apparel Manufacturing Tools may help organize related product and production planning. Apparel Wiki is an independent garment-industry knowledge publication, not a factory, manufacturer, laboratory, certifier, or OEM/ODM provider.
When should a clothing brand finalize its launch price?
Finalize it after the specification, quantity assumptions, quote basis, channel costs, fulfillment method, policy assumptions, and cash plan have been reviewed. A provisional range can guide earlier decisions, but it should not be treated as a firm launch price while major dependencies remain unresolved.
What costs should be included before setting an apparel launch price?
Define the cost scope consistently. Depending on the model, review product cost, packaging, storage, fulfillment, shipping treatment, payment processing, channel deductions, customer service, discounts, returns, and other variable costs connected to the customer promise.
Can I announce a retail price before receiving final production quotes?
You can communicate an indicative price only when its provisional status is clear and the remaining assumptions are understood. Avoid presenting an exact price as final if material, construction, quantity, packaging, or quotation inclusions may still change.
Why can a product’s price change after sampling?
An early sample may use a different route, quantity, material availability, or specification from the intended production plan. Changes to construction, trims, finish, packaging, or quality expectations can also alter the cost basis and require a pricing review.
How do DTC, wholesale, and preorder models affect launch pricing?
They allocate inventory, cash timing, fulfillment work, channel deductions, and customer-service responsibility differently. Compare the specific terms and promises for each model rather than assuming that lower inventory exposure means lower total cost.
What should I do if the final cost makes my planned retail price unworkable?
Review the specification, scope, quantity, channel, fulfillment arrangement, and customer value proposition. You may revise the product, reduce variants, change the commercial model, reposition the price, or hold the launch until the economics are understood.