An apparel raw material price volatility response is a coordinated process for identifying material-cost exposure, assessing its effect on products and commitments, choosing proportionate actions, assigning owners, and reviewing results. It is more disciplined than reacting to a market headline or an uncertain forecast. For context on Apparel Wiki’s editorial support model, see our Sponsor page.
The objective is not to predict every price movement. It is to protect viable products, margin, cash, quality, and delivery commitments while making trade-offs visible. Apparel Wiki is an independent garment-industry knowledge blog, not a manufacturer, factory, testing laboratory, certification body, or sourcing service. The approach below is a repeatable operating framework, not a universal purchasing prescription.
What Is an Operational Response to Apparel Raw Material Price Volatility?
Material-price volatility describes uncertainty or variation in the cost of inputs such as fabric, yarn, trims, or other components over time. An operational response converts that broad concern into decisions connected to actual styles, orders, dates, and business objectives. A useful risk description states what may happen, why the outcome is uncertain, and which objective could be affected.
For example, a new fabric quotation may affect the margin review or purchase decision for a planned style. That does not automatically mean an existing purchase order will be repriced. A supplier quotation, an agreed contract price, and a future purchase estimate are different commercial facts. Whether a price can change depends on the applicable quotation, order status, contract terms, validity period, and direct supplier documentation.
A managed response therefore separates four types of information:
- Verified observations: dated information from a reliable market, company, or transaction source.
- Supplier quotations: commercial information that applies within the stated assumptions and validity period.
- Internal estimates: calculations or planning assumptions prepared for a specific product, order, or scenario.
- Editorial recommendations: practical process guidance that still requires project-specific judgment.
Keeping these categories distinct prevents an estimate from being treated as a confirmed cost, or a general market signal from being treated as a contractual change. It also makes later review easier: a team can see which assumption changed and whether the decision was based on evidence that remains current.
How Should a Team Describe and Map Its Material-Cost Exposure?
Start with the material dependency rather than with a general statement such as “raw material prices are rising.” A workable exposure statement identifies the possible event, its cause or uncertainty, and the affected objective. For instance, “the current fabric quotation may expire before the planned purchase decision, affecting the target margin for Style A” is more actionable than “fabric cost risk is high.” The example is a planning formulation, not a confirmed industry-wide case.
Next, connect the material to the products and commitments that depend on it. Depending on the records available, the map may include the material code, construction or specification, supplier, mill or processor, affected styles, colorways, purchase orders, launch dates, and customer or sales commitments. A bill of materials can show where an input is used; order records can show whether the exposure is committed, pending, or still avoidable; a product calendar can show how much time remains for a decision.
The direct supplier is not always the full dependency. Several suppliers may rely on the same mill, processor, producing region, or upstream input. When that information is available, record the shared dependency instead of counting supplier names as proof of diversification. The purpose is traceability: a team should be able to move from a material concern to the affected products, orders, and commercial commitments.
For each exposure, record what is known, what is assumed, the source and date of the information, and what would change the assessment. Useful questions include:
- Is the material only being considered, quoted, approved, ordered, or already received?
- Which styles, colors, or customer commitments use the same material?
- Which quantity remains exposed, and which quantity is already covered by an applicable agreement or purchase?
- What evidence would confirm, narrow, or invalidate the concern?
- Who needs the information before the next purchasing or product decision?
A risk rating can help prioritize review, but it is a management judgment unless supported by a defensible method and suitable data. “High” should mean that the team has chosen to review the item urgently under its own criteria; it should not be presented as a measured probability. Internal bills of materials, supplier quotations, order records, and product calendars are appropriate evidence sources for this mapping exercise. Claims about a particular material, region, or disruption need separate, dated external support.
Which Variables Change the Business Impact of a Price Move?
The same material-price movement can have very different consequences across products and orders. Begin with the portion of the garment cost that is actually exposed. Material usage per garment, planned quantity, remaining purchase quantity, current quotation or contract terms, purchase timing, and order status all affect the result. A change in a material that is already received may have a different business implication from a change affecting an unapproved future purchase.
Then examine the product’s available response space. A team may be able to review construction, design, specification, sourcing, or selling price, but each option has consequences. A change that appears commercially attractive may affect approved quality, fit, hand feel, color, performance, compliance, customer expectations, or production readiness. These are project-specific judgments, not universal thresholds.
| Variable | Why it matters |
|---|---|
| Material usage and yield | Shows how strongly the input contributes to the product cost and whether waste or cutting assumptions matter. |
| Quote or contract terms | Clarifies whether the relevant cost is an estimate, a valid quotation, or an amount governed by documented terms. |
| Timing and order status | Indicates whether a decision can still change the purchase, product plan, or customer commitment. |
| Other landed-cost components | Currency, freight, duties, and related costs may matter when supported by the team’s records and applicable definitions. |
| Shared product and cash dependencies | One material may affect several SKUs, while inventory decisions may influence cash availability and holding exposure. |
Do not treat a supplier quote, a market index, and landed product cost as interchangeable measures. An index may describe a market reference, while a quotation reflects a supplier’s commercial offer under stated assumptions. Landed cost may include additional components that vary by shipment, currency, route, or applicable charges. The team should preserve the source, date, units, assumptions, and scope of each input before comparing them.
Finally, consider dependencies across multiple styles and commitments. A material decision that protects one SKU may create a shortfall, approval delay, or cash requirement elsewhere. The strongest assessment links measurable inputs, such as usage or quoted cost, to commercial judgments, such as whether a product can absorb a change without compromising its approved requirements. Avoid inventing universal buffers, price triggers, or tolerance levels; each organization must set those from its own records, commitments, and decision rights.
What Actions Can Apparel Teams Compare Before Committing?
Once a team understands which products and commitments are exposed, it can compare responses according to the problem each one addresses. Monitoring may improve visibility, while changing a purchasing or approval timeline may preserve a decision opportunity. An alternative source or material may reduce dependence, and a design or specification review may reduce the amount or type of material required. These are candidates for evaluation, not automatic solutions.
Commercial discussions can also address part of the exposure, depending on the applicable quotation, purchase terms, contract language, and supplier agreement. A clause or insurance arrangement may transfer some loss, but it does not remove the underlying operational risk or guarantee coverage. Deliberately accepting the exposure can be reasonable when the available responses create greater quality, delivery, cash, or customer risk. Acceptance should be recorded as a decision, not treated as inaction.
For each option, record the exposure addressed, accountable owner, decision trigger, required resources, dependencies, expected benefit, downside, and evidence still needed. Before changing a source or material, check effects on fit, color, performance, compliance, approved specifications, production readiness, and delivery. A candidate fabric that appears less expensive is not an equivalent substitute until the relevant product requirements have been reviewed and the necessary validation has been completed.
How Should Teams Set Triggers, Owners, and Review Points?
Triggers should come from the team’s actual decision calendar and records. Useful reference points may include quote validity, an approval milestone, a purchase commitment, a planned launch, a margin tolerance, or a cash constraint. These points differ by organization and product. A market headline alone does not establish that a particular order price has changed, especially when existing terms or commitments govern the purchase.
Ownership should be explicit across sourcing, merchandising, product development, finance, and quality. Sourcing may verify supplier information, product development may assess specification implications, finance may examine exposure in the relevant cost records, and quality may define validation needs. The accountable decision owner should have clear escalation and approval rights, rather than leaving a cross-functional risk to a group with no authority to act.
A concise decision log can preserve the reasoning without becoming a second information system. Include the observed change, source and date, affected materials and products, order or commitment status, assumptions, options considered, selected action, owner, and next review point. Refresh it before a consequential commitment and when orders, supplier conditions, product plans, rules, technology, or cash position change. Close resolved items and add new risks so the record reflects current conditions.
What Are the Limits of a Price-Volatility Response?
Monitoring and planning improve decision quality, but they cannot guarantee a forecast, quotation, supply outcome, margin result, or delivery date. A team may have incomplete information, changing commercial terms, or a product plan that moves before an option can be validated. Keep verified observations separate from supplier statements, internal estimates, and editorial recommendations so the response does not present uncertainty as fact.
Adding suppliers does not automatically remove exposure. Different suppliers may depend on the same mill, processor, origin, transport route, or other upstream input. Likewise, inventory, forward buying, contract provisions, or insurance may be unavailable, unsuitable, or limited by their terms. Each option can introduce its own cash, storage, obsolescence, quality, delivery, or administrative consequences, so the team should assess the full dependency rather than rely on the label of a control.
Price decisions also remain connected to approved product requirements and wider responsibilities. A lower-cost input is not automatically acceptable if it changes fit, appearance, durability, compliance, sustainability commitments, or customer expectations. Document unresolved assumptions and seek qualified commercial, legal, financial, or technical review when the decision depends on specialized interpretation. Apparel Wiki is an independent garment-industry knowledge blog, not a manufacturer, factory, laboratory, certifier, or sourcing service.
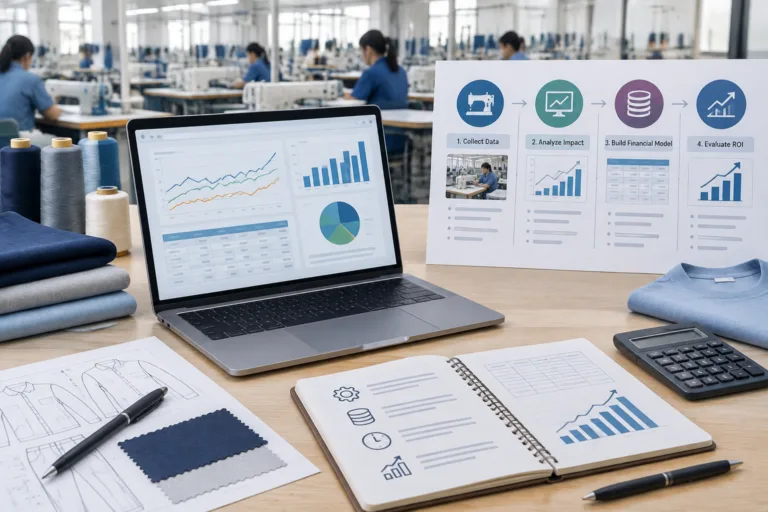
The immediate next step is to map exposed materials to the relevant styles, orders, launch dates, and customer commitments. Verify the current source, date, terms, and scope of each important input, then assign an accountable owner and a review date. This creates a practical starting point for an apparel raw material price volatility response while leaving project-specific thresholds and actions with the team that holds the records and decision rights.
How can an apparel team tell whether a material price change affects an existing order or only future purchases?
Check the applicable quotation, purchase order, contract terms, validity period, order status, and supplier communication. Compare those records with the timing and scope of the reported change. Do not infer that an index movement automatically changes an existing order price.
What information should be included in an apparel raw material price-risk register?
Record the event, affected material and products, order or commitment status, source and date, known facts, assumptions, impacted objective, options, owner, decision status, evidence needed, and next review point. A rating is a prioritization judgment unless supported by a defensible method and data.
Does adding another supplier always reduce apparel material price risk?
No. Suppliers may share upstream mills, processors, origins, logistics routes, or other dependencies. Review the actual supply chain and qualification requirements before concluding that an additional supplier reduces exposure.
When should a team review its response to raw material price volatility?
Review it before consequential purchasing, approval, or launch commitments and whenever material orders, supplier conditions, product plans, rules, technology, or cash position change. Record a planned review date so the assessment does not become obsolete.
How can a brand compare a lower-cost alternative material without compromising product requirements?
Compare the alternative against the approved specification, fit, color, performance, compliance, construction, customer requirements, and production process. Treat it as a candidate requiring project-specific review and validation, not as an equivalent replacement based on price alone.