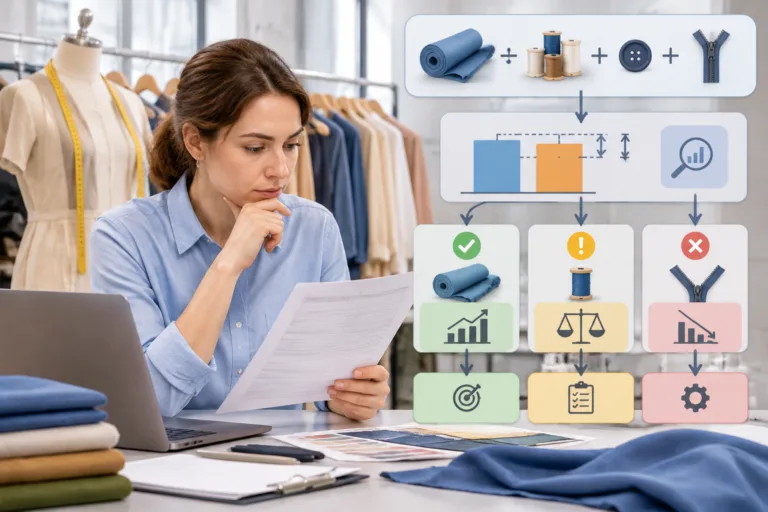
A garment cost variance calculation shows the difference between two comparable cost positions, such as a planned unit cost and an actual or revised unit cost. The useful result is not only the amount of movement. It is an explanation of which quantity, rate, material, labor, process, or scope input changed and why. This independent Apparel Wiki guide explains how to structure that comparison in an Sponsor-supported knowledge publication without treating a learning example as a factory quotation or manufacturing result.
Start by comparing like with like. Keep the garment version, order or time scope, currency, unit, included cost lines, and quantity basis consistent. Then separate usage or quantity movement from rate movement and scope changes. That approach makes an apparel cost sheet variance traceable and keeps a cost comparison distinct from selling price, margin, or total business profitability.
How garment cost variance calculation works
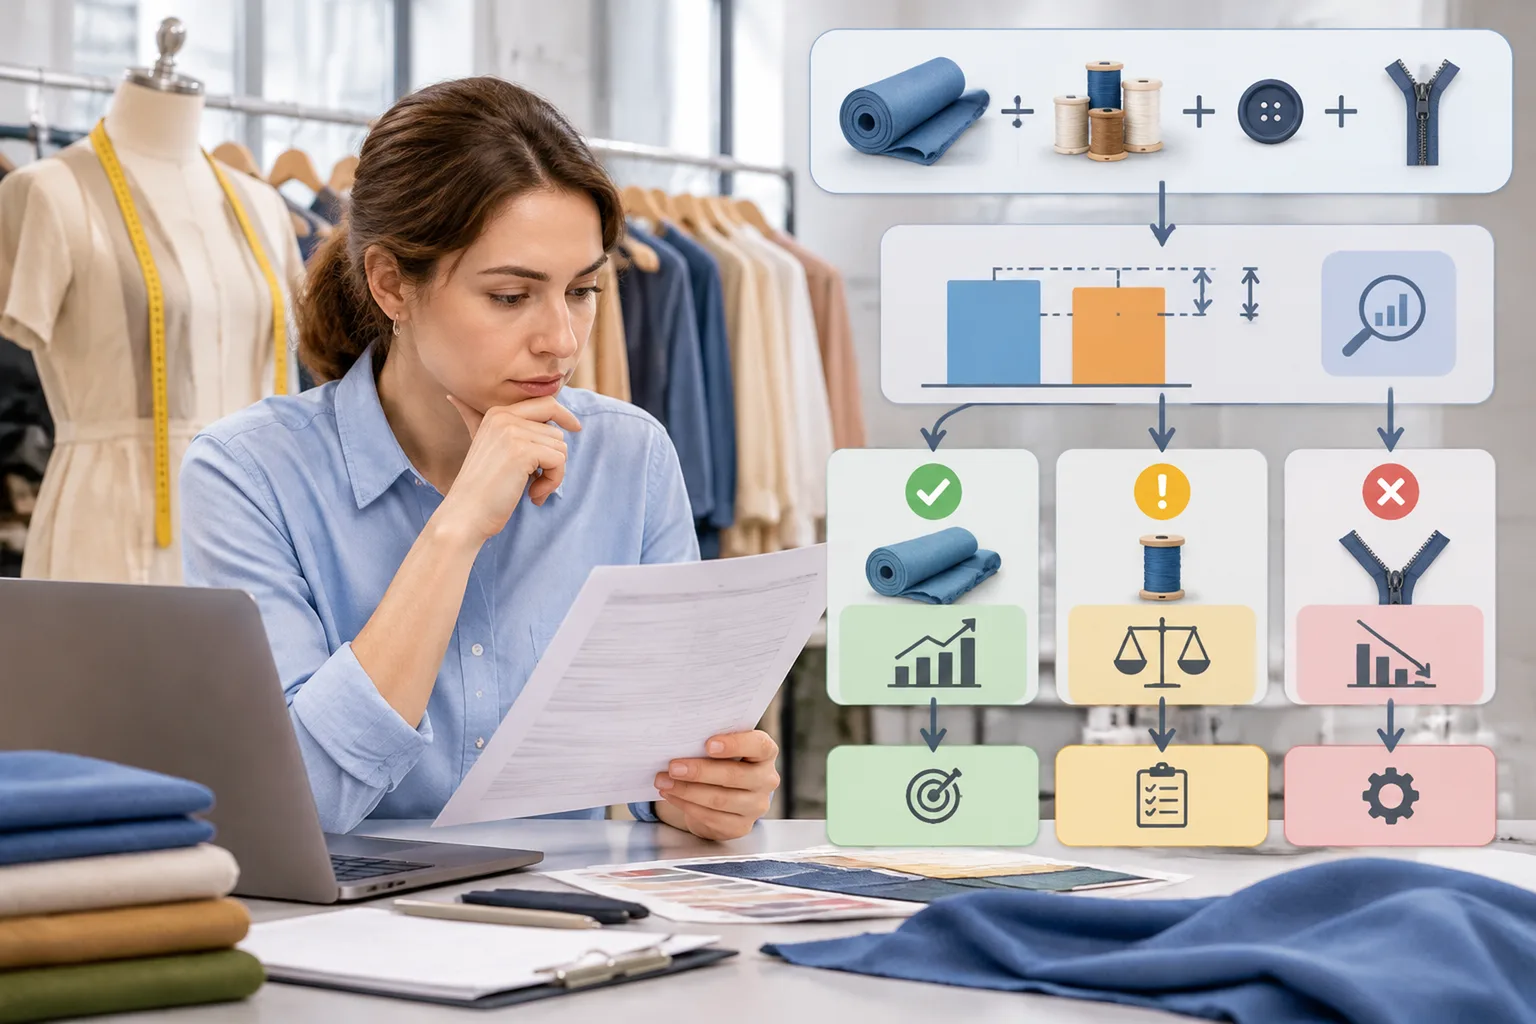
Garment cost variance is the difference between a reference cost and a comparable current cost. The reference may be planned, standard, quoted, revised, or budgeted. The comparison figure may be actual, updated, or otherwise approved for review. In a simple unit-cost structure, the calculation is:
Variance amount = actual or updated unit cost − planned or reference unit cost
For a learning example, record the labels and inputs without inventing garment values: planned unit cost, actual unit cost, and variance amount. A positive result under this subtraction means the compared cost is higher than the reference. A negative result means it is lower. Whether either direction is called favorable or unfavorable depends on the organization’s perspective and the cost being evaluated. For a cost-reduction review, a lower comparable cost may be favorable. For a budget or resource-control review, the reporting convention may be stated differently. Define the convention beside the result instead of assuming that the sign has one universal meaning.
Before calculating a garment cost variance, establish the comparison basis. Use the same garment version, size or order scope, currency, unit of measure, cost inclusions, and material or labor quantity basis. A revised specification, a different size assortment, or a change from per-piece cost to order total can create a difference that arithmetic alone cannot interpret.
Next, ask three questions: which input changed, by how much, and why? A total difference can be decomposed into quantity or usage movement, rate or price movement, and mix or scope movement. If the records cannot be aligned, an unexplained residual may remain. That residual signals a comparability or data problem; it does not prove an operational cause.
Record the source and date for every figure, including the cost-sheet version, supplier document, specification revision, or internal assumption used. This turns the garment cost variance calculation into a traceable review. It remains a cost-sheet comparison, not a change in selling price, profit margin, or overall business profitability.
Build a comparable apparel cost sheet before comparing totals
A total-cost difference is difficult to diagnose when the sheet hides its inputs. An apparel cost sheet should show separate lines for fabric, trims, packaging, direct labor or processing, outside operations where applicable, and any other explicitly included item. For each line, keep the quantity, unit rate, and extended amount visible. The total should be explainable by those components and their stated assumptions.
Material quantities also need a clear flow. Distinguish net usage from marker or cutting loss, spreading or cutting loss, and defect or unusable loss. These are different points in the material calculation. If the purchase quantity already includes a particular allowance, adding that same allowance again duplicates the loss and distorts the cost variance in apparel manufacturing. State the denominator and the included allowance rather than hiding them in one combined number.
Preserve the details that can change comparability: garment version, size range, fabric width, composition or material identity, currency, unit of measure, and cost date. A rate change may be genuine, but it may also reflect a different material identity, purchase unit, currency date, or fabric width. A cost line should therefore carry enough context for another reviewer to understand what was compared.
Use the following review table before explaining a total difference:
| Observable input | Variance implication | Initial review choice | Variables that could change the choice |
|---|---|---|---|
| Quantity differs while the unit rate is comparable | Possible usage or quantity variance | Check the material flow, size scope, and included loss | Width, marker layout, yield, purchase unit, and garment version |
| Unit rate differs while quantity is comparable | Possible price or rate variance | Check the dated source, currency, and material identity | Supplier basis, exchange-rate date, specification, and order terms |
| Cost lines or operations differ | Possible scope or mix variance | Compare approved specifications and included processes | Construction, quality requirement, packaging, size assortment, or substitution |
| Allowance appears in more than one line | Possible duplicate cost or unexplained residual | Map each loss to its quantity basis and remove only confirmed duplication | Purchase quantity, usable quantity, defect definition, and sheet version |
Keep garment-level unit cost separate from order-level totals. Landed costs, channel costs, and period costs may belong to different layers of a model. Freight, insurance, duties, clearance, marketing, returns, and fixed period costs should be shown separately when they are relevant rather than silently folded into a product-cost comparison. Their classification and tax treatment can vary by organization and market, so the sheet should state the chosen treatment.
Separate usage, price, labor, and process variances
After identifying a total movement, review the cost lines in a consistent sequence. For materials, compare planned quantity with actual or updated quantity first. Then compare the planned unit rate with the actual or updated rate. This separates a material cost variance caused by more or less material from one caused by a different price. Check whether the quantity basis changed because of fabric width, weight, usable yield, marker layout, purchase unit, or fabric identity.
For labor and processing, separate the rate from the work content. A rate change concerns the amount assigned to an hour, operation, or processing unit. A time or scope change concerns how much work the garment requires. Added operations, construction changes, rework, quality requirements, or different processing arrangements can alter the total even when the rate is lower. A lower labor rate therefore does not automatically produce a lower garment cost.
Mix and scope changes need their own review. A changed size assortment can alter material usage. A material substitution can change both quantity and rate. New packaging, an added operation, or a revised quality requirement can introduce cost lines that did not exist in the reference sheet. These are not clean price comparisons because the compared garments or processes may no longer have the same cost basis.
A cost-sheet variance identifies a difference; it does not prove the operational cause. Supporting records may include revised specifications, purchase or supplier documents, time records, approved change history, and the relevant sheet version. Without those records, describe the cause as unresolved rather than assigning blame or presenting an assumption as a finding.
For a qualitative example, suppose a lightweight knit is reviewed after its usable width or marker layout changes. The revised layout could alter material usage even if the fabric rate stays unchanged. The result could change again with the size range, fabric behavior, or agreed costing basis. This is an educational conditional scenario, not a real customer project, measured test, or universal production outcome.
Review the relationship between garment specification, construction, and cost rather than treating the spreadsheet as an isolated arithmetic exercise. Separate usage, rate, labor, and process effects first; then investigate the records that explain whether the apparent movement reflects a changed input, a changed scope, or a problem in the comparison itself.
Interpret what the variance means for a costing decision
A calculated variance is evidence of a difference between two cost positions. It is not, by itself, proof of fault, savings, compliance, or production readiness. Before changing a costing decision, classify the difference as a data-quality issue, a specification or scope change, a supplier or market rate movement, a usage or process movement, or an unresolved cause.
Materiality depends on the decision. A small unit difference may become important across a large order scope. A larger isolated difference may reflect a one-time correction or a changed garment version. Compare the result with the relevant baseline and period, using the same currency and unit. Do not compare a garment-level unit cost with an unrelated quotation, landed cost, or period expense and call the result a product variance.
Consider a trim substitution. A lower unit rate may appear favorable, but the revised trim could require a different quantity, packaging method, quality requirement, or processing step. The apparent saving may shrink, disappear, or move to another cost line. The correct conclusion depends on the revised specification and supporting records, not on the rate alone.
Record the affected cost line, comparison basis, owner, evidence, date, and next review point. Define any internal materiality or approval rule for the relevant organization and decision; there is no universal threshold supplied here. Where the evidence does not establish a cause, leave it unresolved and state what record is still needed. This keeps apparel costing analysis useful without turning an arithmetic result into blame or an unsupported commercial recommendation.
Review and improve a garment variance calculation
A repeatable review starts with the arithmetic and then checks the assumptions behind it. For each line, confirm that quantity multiplied by rate produces the stated extension. Reconcile the component differences to the reported total variance. A mismatch may indicate a formula error, a hidden adjustment, a rounding choice, or a difference in cost scope.
Next, check the comparison labels and units. Confirm the garment version, size or assortment scope, material identity, fabric width, currency, exchange-rate date, and cost date. Check whether each figure is stated per piece, per order, or on another basis. Review labor and operation scope as carefully as material scope. A changed operation cannot be treated as a simple rate movement without documenting the change.
Trace each changed line to a source record. Depending on the input, this may be a specification revision, supplier document, purchase record, internal time record, approved assumption, or change history. Mark unresolved inputs instead of silently filling gaps. Also map each loss allowance to its quantity basis. If purchased quantity already includes a particular allowance, adding that allowance again can distort the result.
Use sensitivity analysis as a labeled decision aid when an input is uncertain. Vary one assumption, such as usage, exchange rate, defect allowance, or volume, while holding the others constant. A clearly defined combination of changes can also be shown, but label the assumptions. The output is a scenario, not a prediction of profit, cash flow, or manufacturing performance.
For the next cost-sheet revision, retain the prior baseline and add dated assumptions beside the updated values. Note which specification or commercial input triggered the change, then schedule a recheck when that input changes again. This review method makes a cost sheet easier to explain and keeps a garment cost variance calculation connected to the records that produced it.
Key takeaways for using variance results
A useful garment cost variance calculation explains both the difference and its comparison basis. Compare like with like, separate quantity from rate and scope, and trace every assumption to a dated record. Audit one cost line at a time, checking that loss, freight, tax, and process items appear once and in the intended cost layer.
For an educational next step, compare your own specifications, quantities, rates, and cost inclusions against the reference and updated sheets. Document unresolved assumptions, then check the accounting or organizational method that applies to your decision before revising the cost.
Frequently Asked Questions
What is the difference between a planned garment cost and an actual garment cost?
A planned cost is a reference position, such as a budgeted, quoted, standard, or revised amount. An actual cost is the comparable current position. The difference is meaningful only when garment version, scope, unit, currency, and inclusions match.
How should fabric quantity variance be separated from fabric price variance?
Review the change in fabric quantity or usage separately from the change in unit rate. Then check width, material identity, purchase unit, marker layout, and included loss. A changed basis can make the apparent quantity or price movement misleading.
Why can a lower unit rate still produce a higher garment cost?
Total cost also depends on quantity and scope. A lower rate can be offset by higher usage, a changed trim quantity, an added operation, different packaging, or a revised quality requirement.
How can duplicate waste or loss allowances distort an apparel cost sheet?
When the same loss is included in purchased quantity and added again as a separate allowance, the cost is overstated. Map net usage and each loss basis separately before comparing the reference and updated sheets.
Should freight, duties, and marketing costs be included in garment cost variance?
Include them only when they belong to the defined cost layer being compared. Freight, duties, marketing, returns, and fixed period costs may serve different analytical purposes. Treatment can vary by organization and market.
What records should support a garment cost variance calculation?
Useful records include the dated cost sheets, specifications, supplier or purchase documents, time records, approved assumptions, exchange-rate information, and change history. Each should identify the affected line and comparison basis.