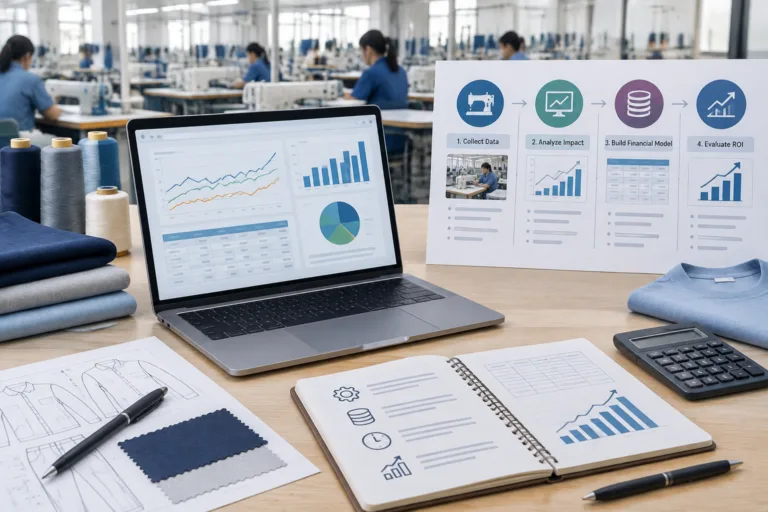
Stress-testing an operating expense budget means applying adverse but plausible changes to its assumptions and observing what happens to contribution, cash needs, break-even activity, and operating capacity. For an apparel business, this can reveal risks hidden by a budget that looks affordable at planned sales volume. Apparel Wiki is an independent educational publication; its editorial independence is described on the Sponsor page, and it is not a manufacturer, supplier, testing laboratory, or financial adviser.
An operating expense budget is a planning view of the recurring costs required to run the business, such as payroll, software, rent, marketing, customer support, and professional services. Its boundaries depend on the company’s accounting policy and management-reporting structure. Product costs, inventory investment, financing costs, and capital expenditure may be reported separately, even though they still affect the business decision being tested.
What Does Stress-Testing an Operating Expense Budget Reveal?
A budget is a set of conditional expectations, not a fixed forecast of what the business will experience. Stress testing changes selected assumptions, either individually or in combination, and shows how sensitive the plan is to those changes. The purpose is not to predict the next quarter or assign a universal risk rating. It is to help founders, merchandisers, sourcing teams, procurement teams, and operators identify which decisions become urgent when trading conditions change.
For example, planned operating expenses may appear manageable when sales volume, realized prices, and payment timing remain on plan. The same expense base can become difficult to support if sell-through weakens, discounts increase, returns rise, or customers pay later than expected. A scenario can also expose operating-capacity risk: a team may reduce spending but lose the design, quality, compliance, or customer-service capacity needed to support future revenue.
The classification boundary should be explicit before any result is interpreted. An operating expense in an internal plan may not have the same treatment in financial statements, tax records, or another company’s management report. A general operating-budget explanation can distinguish day-to-day operating activity from longer-term investment, but that distinction should not be treated as universal across businesses or jurisdictions. Company policy, reporting purpose, and applicable accounting guidance control the final treatment.
In this article, source-backed facts, editorial planning guidance, and hypothetical examples are separate types of claims. Apparel Wiki provides general business-planning education rather than a company-specific budget review. An applied stress test should use the business’s own ledger, contracts, channel reports, inventory records, payroll data, and cash-flow records.
Which Assumptions Should an Apparel Operating Expense Budget Test?
Start with an assumption register rather than a single total expense number. The register should identify each line, its period, currency, unit basis, tax treatment, owner, and inclusion or exclusion rules. This prevents a scenario from combining monthly expenses with annual revenue, mixing tax-inclusive and tax-exclusive values, or counting the same fulfillment or return cost in more than one place.
Revenue assumptions belong in the test because operating expense risk depends on the activity expected to support those expenses. Record units, realized price, channel mix, discounts, returns, cancellations, and payment timing. A wholesale, direct-to-consumer, custom, preorder, or made-to-order model may create different patterns of service work, customer acquisition, inventory exposure, fulfillment responsibility, and collection timing.
Then map the operating expense assumptions. Relevant lines may include employees, contractors, design and development work, software, rent, marketing, logistics administration, compliance activity, professional services, and customer support. The list should reflect the company’s own records rather than an assumed apparel-industry template. If a cost is absent from the register, the scenario may look stronger simply because an obligation was never modeled.
Classify each expense by how it behaves during the tested period:
- Committed costs: obligations that continue for a defined period under employment arrangements, leases, contracts, subscriptions, or other commitments.
- Activity-linked costs: expenses that change with orders, customers, shipments, service volume, or another operating driver.
- Stepped costs: expenses that remain stable within a capacity range but increase when another employee, facility, system, or service level is required.
- Discretionary or partly variable costs: spending that management may pause, delay, renegotiate, or resize, subject to customer, quality, contractual, and compliance effects.
Finally, record links between operating expenses, inventory, and working capital. Product launches can require development spending before revenue arrives. Purchase commitments, development calendars, minimum commitments, and slow-moving stock can limit how quickly the business reduces cash use. These links matter because lower inventory does not automatically mean lower total cost or lower business risk.
How Can You Build Useful Downside Scenarios?
A practical operating expense budget stress test usually needs a base case, a downside case, and a severe-but-plausible case. Each case should state the changes being made to sales volume, realized price, returns, variable costs, fixed expenses, collection timing, and inventory conversion. Scenario labels describe conditions for analysis; they are not predictions or claims about what the market will do.
Test combined pressures rather than changing only one line. Weaker sell-through may occur alongside heavier discounting, higher returns, slower collections, and continued product-development commitments. A single-variable sensitivity can show which input matters mathematically, but a combined scenario is more useful for deciding whether the team must change launch timing, purchase commitments, channel emphasis, or discretionary spending.
Channel structure also belongs in the scenario design. Wholesale, DTC, custom, preorder, and made-to-order models distribute customer acquisition, inventory, fulfillment, service, and payment risks differently. A channel with lower inventory exposure may still require more service work or produce slower collection. Conversely, reducing an inventory commitment may protect cash while limiting assortment, launch capacity, or customer experience.
| Scenario element | Base case | Downside case | Severe case | Decision use |
|---|---|---|---|---|
| Assumption | Planned value | Adverse but plausible change | Multiple pressures combined | State the rationale |
| Financial effect | Operating result and cash need | Contribution and cash exposure | Capacity and funding pressure | Compare consistently |
| Leading indicator | Expected trend | Early deterioration | Trigger condition | Assign an owner |
| Proposed response | Continue monitoring | Review options | Approve a staged action | Record evidence required |
Keep the matrix small enough for accountability. For every changed assumption, document the historical evidence or management rationale behind it. Do not describe a scenario value as an industry average without validated evidence. Compare operating result, cash requirement, inventory exposure, contribution, and the point at which management action would be reviewed.
How Do Contribution and Break-Even Connect Operating Expenses to Risk?
Unit contribution connects sales activity with the operating expenses that must be covered. In a simplified planning model, unit contribution equals realized net revenue minus the explicitly included unit variable costs. Depending on the business’s defined scope, these may include product cost, fulfillment, channel commission, payment costs, and an assumed return cost. Contribution is not automatically the same as gross margin; the two are comparable only when their cost boundaries are defined identically.
Consider this hypothetical illustration using consistent currency units. A net receipt of 50 less product cost of 20, fulfillment of 6, commission of 5, and an assumed return cost of 3 produces a unit contribution of 16:
50 – (20 + 6 + 5 + 3) = 16
For a simplified single-product model, break-even volume can be expressed as fixed operating expenses divided by positive unit contribution. If hypothetical fixed operating expenses are 4,800 and unit contribution is 16, the result is 300 units:
4,800 ÷ 16 = 300 units
These values are illustrations, not benchmarks, forecasts, or recommendations. The expense boundary must be checked carefully to avoid double-counting product, fulfillment, commission, or return costs. The formula is a planning aid, not proof of profitability or cash solvency. It also changes with product mix, channel mix, discounting, returns, variable-cost definitions, and timing. If contribution is zero or negative, simply increasing volume does not solve the problem under this model.
What Other Signals Should Be Tested Alongside the Expense Total?
An operating expense total can look controlled while the business becomes more exposed elsewhere. Revenue growth may arrive with weaker contribution, heavier discounting, longer collection periods, rising returns, or older inventory. For an apparel business, these effects can change the amount of cash available for product development, purchasing, fulfillment, and customer support before the annual budget visibly misses plan.
Compare budgeted cash timing with actual cash timing rather than relying only on accrued revenue and expense totals. A wholesale order, direct-to-consumer sale, preorder, or custom project can place customer payment, fulfillment work, and inventory requirements at different points in time. The stress test should show when cash is received, when commitments must be paid, and how long inventory or receivables remain outstanding.
Inventory age is another important signal. A business may reduce a discretionary expense while continuing to carry product-development commitments, launch costs, purchase obligations, or slow-moving stock. Lower inventory is not automatically lower total cost or lower business risk if reducing it requires deeper discounting, additional service work, or a poor customer experience.
Classify expenses by the action available to management. Some may be paused, delayed, renegotiated, replaced, or scaled with activity. Others continue because of contracts, staffing arrangements, quality work, customer commitments, or operational dependencies. This classification should be documented rather than assumed, and any proposed change should be checked against applicable agreements and requirements.
Useful leading indicators can include sell-through, cancellations, returns, collections, inventory age, utilization, and contribution by channel or product group. None has a universal target or threshold. Their value comes from showing a developing problem early enough for the responsible team to review the assumptions and decide whether action is needed.
How Should an Apparel Team Respond When a Scenario Fails?
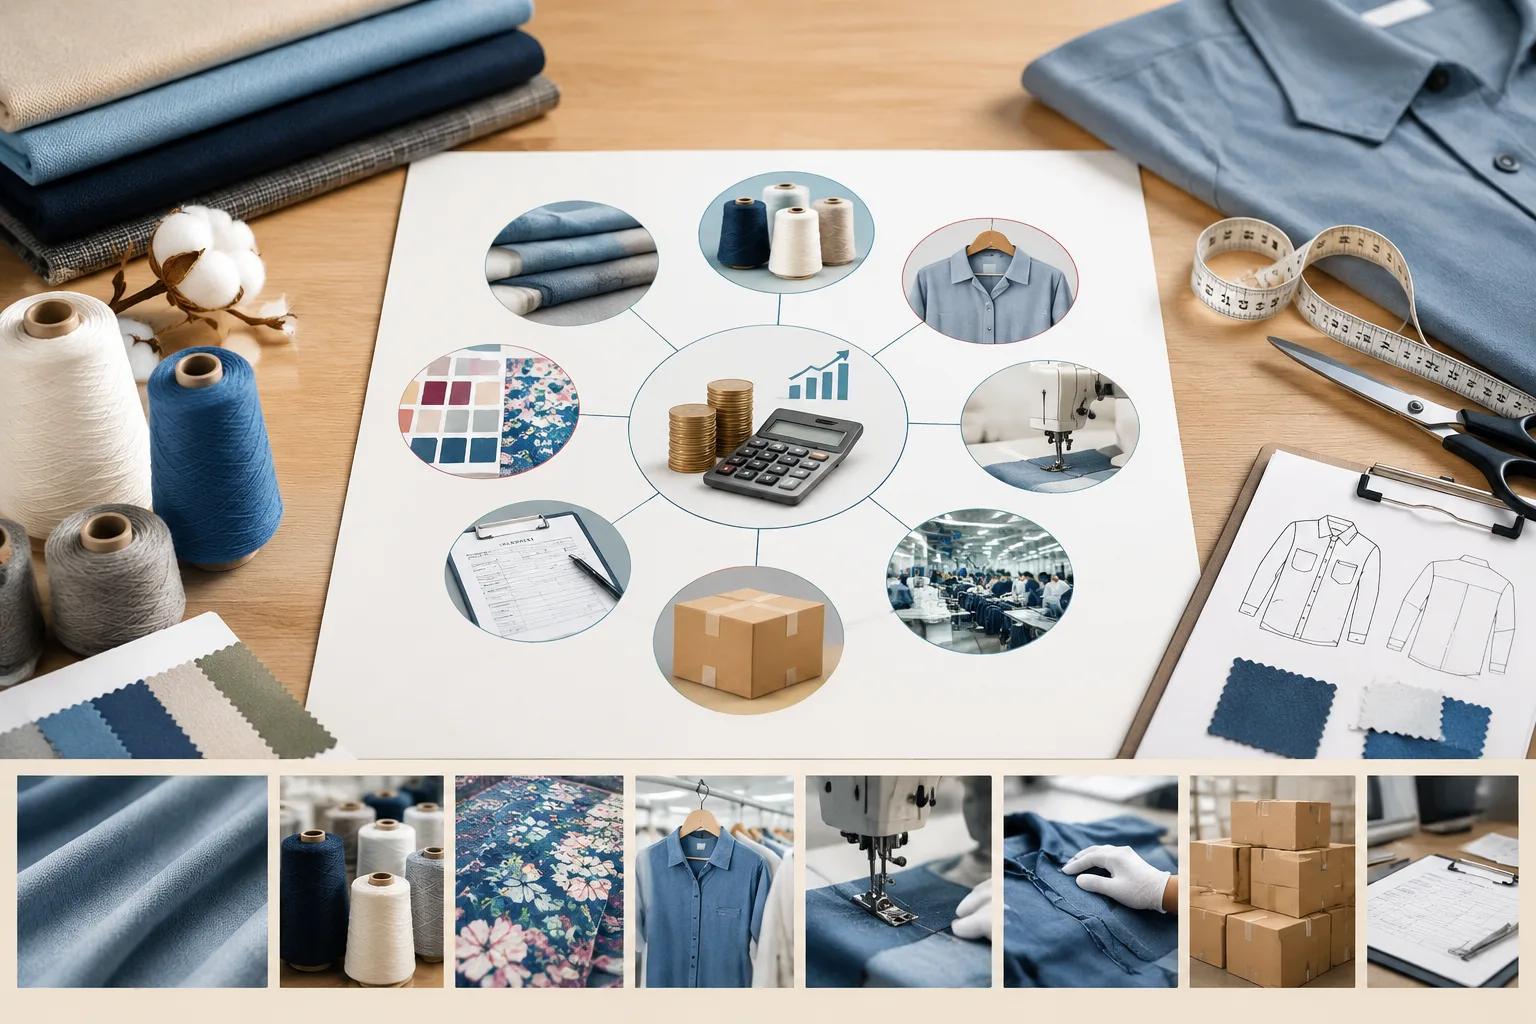
A failed downside scenario is a management signal, not an automatic instruction to cut every expense. Begin by defining review triggers that fit the company’s reporting system. Examples may include a material variance from plan, deteriorating contribution, slower collections, rising return activity, or inventory aging. The trigger should identify when a review starts, not claim that one number applies to every apparel business.
Assign each response to an owner. Finance may maintain the model and cash view; merchandising may review product and channel mix; product development may assess launch timing; sourcing may examine commitments; marketing may revisit planned activity; and operations may evaluate service capacity. Clear ownership helps distinguish an approved response from an untested suggestion.
Prioritize actions by reversibility and customer impact. A team might pause discretionary spending, revisit a launch sequence, adjust purchase commitments where permitted, or revise channel and pricing assumptions. Quality-critical work, compliance-related activity, and commitments affecting customers should remain visible in the decision record. A reduction that appears helpful in one expense column may create larger inventory, service, quality, or cash problems elsewhere.
Model each proposed action across revenue, contribution, inventory, capacity, customer experience, and cash. Do not assume that reducing an operating expense improves the result if the action delays a sale, increases returns, damages product quality, or shifts work into a more expensive period. Record the assumption changed, the owner, the expected signal, and the evidence that will confirm or reject the action.
After the decision, schedule a reforecast rather than treating the response as permanent. The next review should compare actual results with the scenario, identify which assumptions moved, and determine whether the business is returning to the base case or developing a different risk pattern.
What Are the Limits of an Operating Expense Stress Test?
An operating expense stress test is conditional on its assumptions. It does not predict demand, guarantee funding, or prove that an apparel business model is viable. Its result means that a defined combination of revenue, cost, timing, inventory, and operating assumptions produces a particular planning outcome. Change the assumptions or the cost boundaries, and the conclusion may change.
Single-product break-even logic is especially limited for businesses with multiple products, channels, currencies, launch periods, or fulfillment models. A useful review may require sales mix, timing, capacity, inventory conversion, collections, committed purchases, and cash-flow analysis in addition to the simplified volume calculation. The model should also reconcile its definitions with the company’s financial and management reports.
A reusable planning checklist is:
- Define the period, currency, cost scope, and reporting purpose.
- Gather actual sales, expense, cash, inventory, return, and collection data.
- Classify committed, discretionary, stepped, and activity-linked costs.
- Document revenue, pricing, channel, inventory, and timing assumptions.
- Build base, downside, and severe-but-plausible scenarios.
- Test contribution, cash requirement, inventory exposure, and operating capacity.
- Assign review triggers, owners, and proposed responses.
- Reconcile the model with actual results and reforecast regularly.
For the next step, turn this checklist into an internal assumption register and scenario matrix. Apparel Wiki’s Apparel Manufacturing Tools can provide a related starting point for organizing operational planning, but the budget itself must use the company’s own records, definitions, approvals, and professional advice where decisions carry material financial or legal consequences.
Frequently Asked Questions
What is stress-testing an operating expense budget?
It is the process of applying adverse but plausible changes to budget assumptions and observing the effects on contribution, cash needs, break-even activity, inventory exposure, and operating capacity.
Which operating expense assumptions create the greatest risk for an apparel business?
Risk often comes from assumptions about sales volume, realized price, discounting, returns, collections, product launches, staffing, marketing, development work, purchase commitments, and expenses that cannot be reduced quickly.
How does unit contribution differ from gross margin when testing a budget?
Unit contribution subtracts the explicitly defined variable costs needed for the planning question. Gross margin may use a different cost boundary. They are comparable only when both calculations include the same costs.
Can a break-even calculation prove that an apparel business is profitable?
No. A simplified break-even result shows the activity needed to cover defined fixed expenses under stated assumptions. It does not prove cash solvency, demand, funding capacity, product viability, or profitability across multiple products and channels.
How should inventory, returns, and cash timing be included in an operating expense stress test?
Include them as explicit assumptions and review signals. Test how returns affect contribution, how inventory age affects conversion and discounting, and when customer receipts and business payments occur.
What should a business do when its downside scenario fails?
Start a defined review, assign owners, validate the assumptions, and compare reversible actions across revenue, contribution, inventory, capacity, customer experience, and cash. Expense reduction is only one possible response.